The RBA May Raise Rates, So Why Are Some Banks Cutting Mortgage Rates?
The RBA Is Expected to Hike Rates on Tuesday. So Why Are Some Banks Cutting Mortgage Rates?
Australia's mortgage market is doing something that can look contradictory.
The Reserve Bank of Australia is facing pressure to raise interest rates again.
Yet at the same time, some banks have been cutting selected home-loan rates.
Commonwealth Bank reduced pricing across selected mortgage products earlier this year. ANZ and Westpac followed, while Macquarie also moved rates lower as lenders competed more aggressively for borrowers. ABC reported that dozens of lenders had reduced variable mortgage rates, with some competitive offers beginning around 5.69% at the time of its 14 September report. ABC News
Meanwhile, the official RBA cash-rate target remains 4.35%, with the next decision due at 2:30 pm on 29 September 2026. Reserve Bank of Australia
CBA economists currently expect the RBA to increase the cash rate by 25 basis points to 4.60% at that meeting, while recent market pricing has also indicated a very high probability of another increase. The RBA itself has not pre-committed to that decision. CommBank
So how can mortgage rates fall while the central bank may be preparing to raise rates?
Because the cash rate and the mortgage rate an individual borrower actually receives are not the same thing.
The Cash Rate Influences Mortgage Rates. It Does Not Set Them.
The RBA describes the cash rate as the overnight interest rate banks pay when borrowing funds from one another.
It is one of the most important interest rates in the Australian economy because movements in the cash rate influence mortgage rates, deposit rates and other borrowing costs. Reserve Bank of Australia
But "influences" is different from "determines."
The RBA does not tell each bank exactly what interest rate it must charge on a:
60% LVR owner-occupier mortgage,
90% LVR first-home-buyer loan,
investment loan,
fixed-rate mortgage,
interest-only mortgage,
or refinance application.
Each lender sets its own pricing.
That pricing reflects several forces at once.
What Actually Determines Your Mortgage Rate?
A lender may consider:
the RBA cash rate
wholesale funding costs
deposit costs
competition between lenders
how aggressively the lender wants new mortgage customers
your loan-to-value ratio
owner-occupier versus investment purpose
principal-and-interest versus interest-only repayments
fixed versus variable structure
loan balance
property type and location
refinance versus purchase
the lender's risk appetite
profitability targets
This means two borrowers can apply for mortgages on the same day and receive materially different rates.
And two banks can react differently to exactly the same RBA decision.
Competition Is Creating a Mortgage "Rate War"
The key factor behind many of the recent cuts is competition.
ABC reported that lenders are fighting for a larger share of a smaller mortgage market as property activity slows.
Mortgage broker Julian Choo told ABC that dozens of lenders had cut variable rates and that many of the strongest offers were aimed at attracting new customers. ABC News
Canstar identified the same trend.
By 10 August, 49 lenders offered at least one variable rate below 6%, compared with 38 lenders at the beginning of June.
Canstar also found 31 lenders had cut new-customer variable rates since early June. Canstar
The RBA has independently observed this behaviour.
Its August Statement on Monetary Policy said variable mortgage rates rose by almost 75 basis points between January and June as previous RBA increases flowed through.
Yet since June, some lenders had reduced advertised variable rates on selected products by as much as 20 to 30 basis points because of continued competition and efforts to protect market share. Reserve Bank of Australia
So the market can experience both forces simultaneously:
RBA pressure pushing rates higher.
Competition pushing selected mortgage offers lower.
Banks Are Fighting Over a Smaller Pool of Borrowers
This is where the current market becomes particularly interesting.
Lenders do not simply want mortgage customers.
They want profitable mortgage customers.
When property transactions slow and fewer borrowers are taking out new loans, banks have to compete harder for the remaining applicants.
That can encourage lenders to reduce margins.
Imagine a lender normally wants to earn a particular margin above its cost of funding.
If mortgage volumes are strong, it may not need to offer aggressive pricing.
But if applications slow sharply, the bank might accept a smaller margin to win more customers.
Another lender may decide not to compete.
A third might target only certain LVR bands.
That is why mortgage pricing can become fragmented.
New Customers Can Receive Different Pricing From Existing Customers
This is one of the most important parts of the current story.
ABC's investigation found that existing borrowers were not necessarily receiving the same discounts being advertised to new customers.
Julian Choo said lenders often reserve stronger deals for customers they are trying to acquire and may not proactively offer those rates to existing borrowers. ABC News
That does not mean every existing borrower is paying too much.
Some longstanding customers already have highly competitive discounts.
But it does mean borrowers should not assume:
"My bank has cut rates, therefore my mortgage rate has also fallen."
Check the actual rate on your loan.
The "Loyalty" Problem Has Not Completely Disappeared
Mortgage borrowers sometimes stay with the same lender for years without reviewing their rate.
That creates an opportunity for banks.
A customer who rarely compares the market may remain on a higher rate even while the lender advertises sharper pricing to attract someone new.
From the bank's perspective, reducing an existing customer's rate unnecessarily reduces revenue.
From the borrower's perspective, asking for a pricing review could potentially produce a saving.
That makes mortgage reviews particularly relevant in a market like this.
You May Not Need to Refinance to Benefit From Competition
Refinancing gets most of the attention.
But before switching banks, an existing borrower can ask their current lender for a rate review.
A simple question can be:
"What is the best rate you can offer me on my current home loan?"
The lender might:
reduce the rate,
offer a retention discount,
move the borrower to a different product,
or decline to make any change.
If the lender reduces the rate sufficiently, the borrower may avoid:
discharge fees,
new application costs,
property valuation complications,
new LMI considerations,
and the administrative work of refinancing.
There is no guarantee it will work.
But it can be worth asking.
LVR Can Completely Change the Rate Available to You
Loan-to-value ratio is one of the biggest reasons advertised mortgage rates can be misleading.
LVR compares the mortgage amount with the value of the property.
For example:
Property value: $800,000
Loan: $640,000
LVR: 80%
Another borrower buying the same property with a $720,000 loan would have:
LVR: 90%
The second borrower can potentially face:
different interest rates,
fewer lender choices,
LMI,
or tighter lending criteria.
So when you see a lender advertising a highly competitive rate, check the required LVR.
The headline rate may apply only to borrowers with substantial equity.
A Falling Property Market Can Make Refinancing Harder
This is particularly relevant now.
Property values have weakened in several Australian markets.
Someone who bought recently with a small deposit may have seen their equity decline.
Even if another lender advertises an excellent refinance rate, the borrower may discover that the new property valuation pushes their LVR above 80%.
That can affect:
rate eligibility,
refinancing approval,
and potential LMI costs.
So the best advertised mortgage rate is irrelevant if the borrower cannot qualify for it.
Loan Purpose Matters Too
Owner-occupiers and investors are often priced differently.
Principal-and-interest borrowers may receive different pricing from interest-only borrowers.
First-home buyers may access government guarantee programs or special lender policies.
Professional borrowers can sometimes receive LMI waivers.
Self-employed borrowers may benefit from lenders with more flexible income-assessment policies.
That is why asking:
"Which bank has the lowest mortgage rate?"
is often the wrong question.
A better question is:
"Which lender has the strongest overall option for my specific circumstances?"
Fixed Rates Can Move Differently From Variable Rates
Fixed and variable mortgages also behave differently.
Variable mortgage rates are closely influenced by:
the cash rate,
short-term bank funding,
and lender competition.
Fixed rates are more influenced by expectations about where interest rates and wholesale funding costs are likely to be in the future.
That means a lender can:
raise fixed rates,
cut a selected variable rate,
and leave another product unchanged
all within a short period.
There is nothing inherently contradictory about that.
The products are being priced against different risks and funding conditions.
Funding Costs Still Matter
Banks cannot sustainably offer mortgages without considering how much it costs them to obtain the money they lend.
Australian banks fund their mortgages through a combination of:
customer deposits,
wholesale debt markets,
bank bonds,
and other funding sources.
The RBA reported that lenders' funding costs had increased during 2026 as higher cash rates flowed through into deposits and wholesale debt. Reserve Bank of Australia
But banks do not all have exactly the same funding mix.
One lender may have a large base of relatively inexpensive deposits.
Another may rely more heavily on wholesale markets.
A third may aggressively sacrifice margin temporarily to grow market share.
That contributes to rate differences.
What Does a 0.50% Rate Difference Actually Mean?
Rate competition can sound insignificant when expressed in basis points.
But a difference of half a percentage point can become meaningful on a large mortgage.
Consider an illustrative:
Mortgage: $600,000
Remaining term: 25 years
Principal-and-interest repayments
At 5.69%, the approximate repayment is:
$3,753 per month.
At 6.19%, it is approximately:
$3,936 per month.
Difference:
about $183 per month.
That is roughly:
$2,200 per year.
This example excludes fees and assumes the rates remain unchanged.
But it illustrates why borrowers should pay attention to relatively small pricing differences.
What if the RBA Raises Rates by 0.25%?
Now take the same $600,000 mortgage.
If the interest rate moved from 5.69% to 5.94%, the monthly repayment would rise by roughly $91 under the same 25-year assumption.
A borrower who had already negotiated a 0.50 percentage-point discount might therefore remain better off than someone who never reviewed their rate, even after a future RBA increase.
This is the key point.
The direction of the cash rate matters.
But the starting rate on your own mortgage matters too.
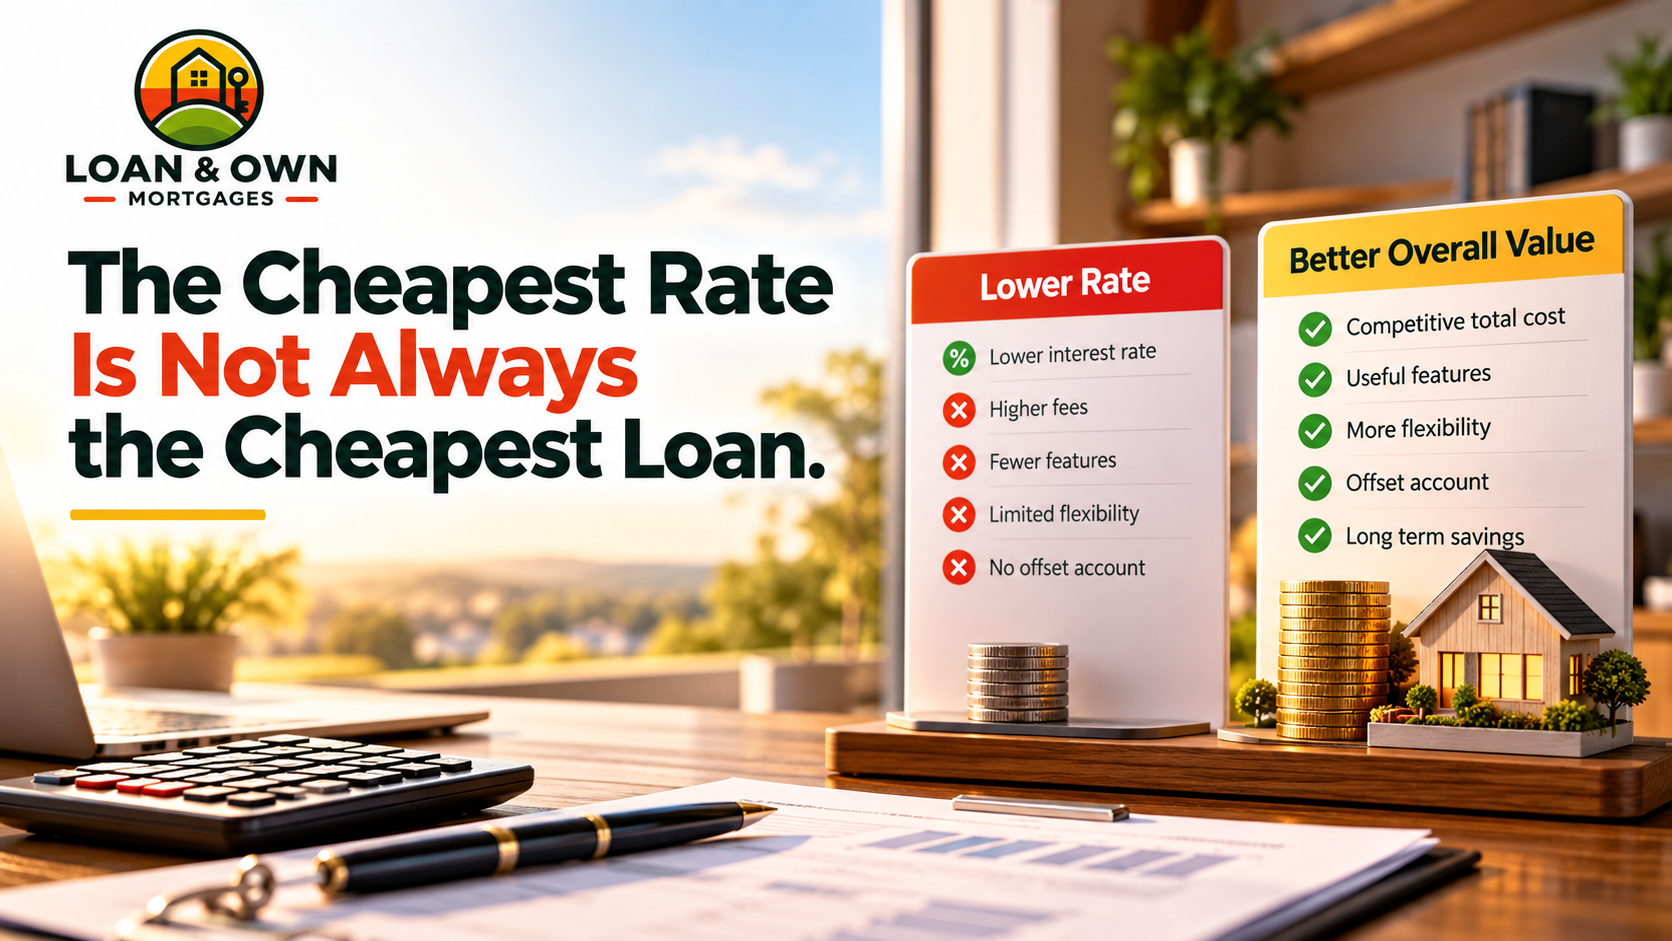
The Cheapest Rate Is Not Always the Cheapest Loan
A borrower should not choose a mortgage solely because one lender advertises the smallest percentage.
The total loan should be compared.
Look at:
interest rate,
comparison rate,
annual fees,
offset account fees,
application charges,
valuation costs,
discharge fees,
cashback conditions,
repayment flexibility,
redraw,
loan term,
and any LMI.
A mortgage with a slightly higher interest rate may sometimes produce a better result if it has useful features and lower fees.
The reverse can also be true.
Be Careful With Cashback Offers
Mortgage competition sometimes creates large cashback incentives.
A borrower might receive several thousand dollars for refinancing.
That sounds attractive.
But a cashback payment is generally received once.
Interest is paid continuously.
A lender offering $3,000 cashback but charging a materially higher interest rate can become more expensive over time than a lender with no cashback.
The right comparison is the total financial outcome.
Do Not Accidentally Reset Your Mortgage for Another 30 Years
This is another refinancing trap.
Imagine you have 20 years left on your mortgage.
You refinance to a new lender and select a fresh 30-year term.
The monthly repayment could fall substantially.
That might look like a huge saving.
But some of the lower payment comes from extending the mortgage for another ten years.
That can increase total lifetime interest.
When comparing refinance options, review:
current remaining term,
proposed term,
monthly repayment,
and estimated total interest.
A Rate Review Does Not Mean You Must Switch
A mortgage review has one purpose:
to understand whether the current loan is still competitive.
The answer may be:
stay exactly where you are.
Your existing lender might already be offering excellent pricing.
Or switching costs may exceed the benefit.
Or you may have valuable features you would lose by refinancing.
That is still a successful review because you now understand your position.
The RBA Decision Is Tomorrow, but Borrowers Do Not Need to Wait
As of 28 September, the cash rate remains 4.35%, and the RBA's next decision is scheduled for tomorrow, 29 September. Reserve Bank of Australia
CBA expects a 25-basis-point increase to 4.60%, citing stronger inflation pressures, higher oil prices and more hawkish RBA commentary. CommBank
Reuters reported last week that financial markets were assigning roughly a 95% probability to another increase, although Governor Michele Bullock had not committed the Board to a particular decision. Reuters
Borrowers should therefore treat another hike as a scenario to prepare for rather than a guaranteed outcome.
But the important point is:
you do not need to wait for tomorrow's announcement to check your mortgage.
Why Would a Bank Cut Rates Just Before an RBA Hike?
Because it may still make commercial sense.
Suppose a lender believes the RBA will raise the cash rate by 0.25%.
The bank could still cut its new-customer mortgage rate today by 0.20%.
If the RBA later increases the cash rate, the bank may pass some or all of that increase through.
The new borrower could still end up with a competitive rate.
Meanwhile, the lender has successfully attracted a customer who may stay for years.
Mortgage pricing is therefore strategic.
It is not simply an automatic cash-rate formula.
Competition Could Become Even More Important if Housing Credit Slows
The RBA itself has linked recent selective mortgage cuts with competition for market share as housing-credit growth is expected to slow. Reserve Bank of Australia
That is worth watching.
If fewer people:
buy properties,
upgrade,
invest,
or refinance,
banks have fewer opportunities to originate mortgages.
The competition for strong borrowers can therefore become even more intense.
That could create opportunities for borrowers who actively compare.
But Existing Customers May Need to Ask
This is perhaps the most actionable message from the current market.
Banks may advertise aggressive pricing.
But they may not automatically apply it to everyone already on their books.
That means existing mortgage holders should know:
their current rate,
their current loan balance,
their approximate property value,
their LVR,
and what comparable lenders are offering.
Then they can have a meaningful conversation with their current bank.
A Simple Mortgage Health Check
A useful home-loan review can start with six questions:
What interest rate am I currently paying?
What is my remaining mortgage balance?
What is my property likely worth today?
What is my approximate LVR?
What rate would my existing lender offer if I asked for a review?
What would switching actually save after all fees and costs?
You do not need to wait for mortgage stress before answering these questions.
The Bigger Lesson: The Mortgage Market Is Not One Single Rate
News headlines often reduce the mortgage market to one number.
The RBA cash rate.
But borrowers live in a much more complicated market.
There are thousands of combinations involving:
lenders,
LVR bands,
borrower types,
fixed periods,
variable rates,
offset products,
investor loans,
owner-occupier loans,
and refinancing policies.
That is why the mortgage market can appear to move in opposite directions.
The RBA can be preparing to tighten monetary policy while an individual bank simultaneously cuts a selected mortgage product.
Both can be true.
The RBA May Raise Rates. Your Bank May Still Want Your Business.
Australia's mortgage market currently contains two competing forces.
The first is monetary tightening.
The RBA cash rate is 4.35%, and another increase remains a significant possibility at tomorrow's meeting. Reserve Bank of Australia
The second is intense lender competition.
The RBA, ABC and Canstar have all documented lenders cutting selected mortgage rates despite the higher-rate environment. Reserve Bank of Australia
That creates an unusual opportunity.
Borrowers cannot control what the RBA decides.
But they can control whether they compare their home loan.
Is Your Current Mortgage Rate Still Competitive?
At Loan & Own Mortgages, we help Australian homeowners, buyers and investors compare their existing mortgage against current lender options.
That can include reviewing:
your current rate,
LVR,
equity,
loan features,
refinancing costs,
available lender pricing,
and whether your existing lender may offer a better deal.
The RBA cash rate matters.
But it is not necessarily the rate you need to accept.
Before assuming higher official rates mean every mortgage option is becoming more expensive, compare what lenders are actually offering.
Speak with Loan & Own Mortgages to review your home loan.
Data sources
ABC News, 14 September 2026: Australian lenders have been cutting selected variable mortgage rates as competition intensifies for fewer borrowers. ABC reported competitive variable rates beginning around 5.69% at the time, while brokers said existing customers were not necessarily receiving the same pricing as new borrowers. ABC News
Reserve Bank of Australia: The cash-rate target remains 4.35%, effective from 12 August 2026, with the next monetary-policy update scheduled for 2:30 pm on 29 September. Reserve Bank of Australia
RBA August 2026 Statement on Monetary Policy: Variable mortgage rates increased nearly 75 basis points between January and June, but selected lenders subsequently reduced advertised variable rates by as much as 20 to 30 basis points amid strong competition for mortgage market share. Reserve Bank of Australia
Canstar, August 2026: 49 lenders were offering at least one variable mortgage rate below 6%, up from 38 at the beginning of June, while 31 lenders had cut new-customer variable rates since June. Canstar
Commonwealth Bank, September 2026: CBA economists expect the RBA to raise the cash rate by 25 basis points to 4.60% on 29 September, citing higher oil prices, stronger inflation data and recent RBA signals. CommBank
Reuters, 22 September 2026: Financial markets were pricing approximately a 95% probability of another RBA increase, while Governor Michele Bullock emphasised that the Board had not pre-committed to the September decision. Reuters
This article provides general information only and does not constitute personal financial, credit, investment, tax or legal advice. Mortgage rates, lender policies, LVR requirements, fees and refinancing eligibility can change and depend on individual circumstances.
