Your Mortgage Rate Isn't Controlled by Just One Number: Why Oil, Bond Yields and Global Markets Matter
Your Mortgage Rate Isn't Controlled by Just One Number
When Australians think about mortgage rates, most attention naturally goes to the Reserve Bank of Australia.
Did the RBA raise rates?
Will it hold?
When will rates eventually fall?
Those questions matter.
But they do not tell the entire mortgage-rate story.
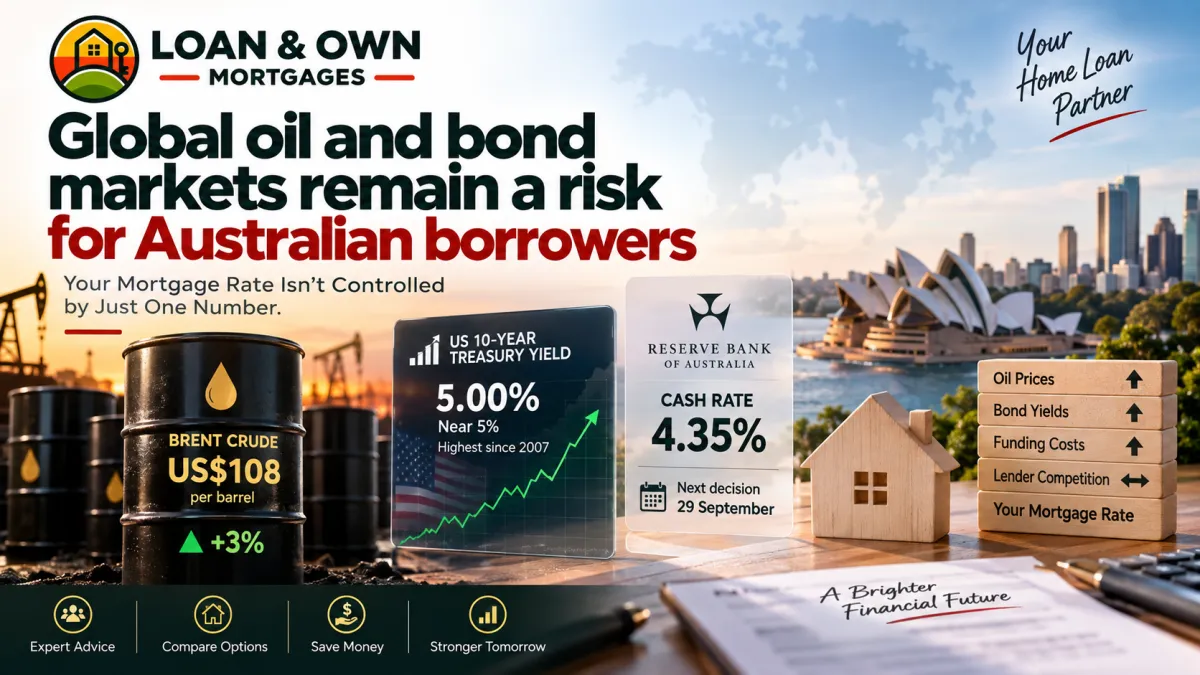
Australia's cash-rate target currently sits at 4.35%, and the RBA's next monetary-policy decision is scheduled for 29 September 2026. (Reserve Bank of Australia)
Yet while borrowers wait for that announcement, global financial conditions are changing rapidly.
Oil prices are above US$100.
Long-term global bond yields have surged.
The benchmark US 10-year Treasury yield has moved through 5%.
Inflation expectations are rising again.
And those developments can eventually influence the cost of funding mortgages in Australia, even though none of them is the Australian cash rate.
That is why borrowers should understand that their mortgage rate is connected to a much bigger financial system.
Oil Has Returned as an Inflation Risk
Brent crude traded around US$108.20 a barrel on 15 September after fresh attacks on Saudi Arabian energy infrastructure increased concerns about supply disruption.
Reuters reported that Saudi Arabia's East-West Pipeline had been forced offline, while continued restrictions around Gulf shipping raised fears that disruptions could persist. (Reuters)
Oil prices matter to Australian borrowers for two reasons.
The first is inflation.
Higher crude prices can flow into petrol and diesel prices, increasing household transport costs.
They can also increase freight, aviation, manufacturing, agricultural and construction costs.
The RBA estimates that global crude oil prices represent around 40% of the final Australian retail fuel price, with changes potentially flowing through to domestic fuel prices within one to two weeks. (Reserve Bank of Australia)
The Bank also estimates that a 10% increase in domestic fuel prices can directly add a little over 0.3 percentage points to headline inflation over one to two quarters. (Reserve Bank of Australia)
That does not mean a 10% rise in Brent automatically raises Australian CPI by 0.3 percentage points.
Exchange rates, refining margins, taxes, shipping costs and wholesale fuel markets also matter.
But it illustrates why central banks closely watch sustained energy-price increases.
Why Higher Oil Could Affect the RBA
The RBA is trying to return inflation sustainably to its target range.
If higher energy prices push petrol, transport and business costs upward, inflation could remain elevated for longer.
That can affect expectations around monetary policy.
Instead of asking only whether the RBA will raise rates in September, borrowers should also think about another possibility:
What if inflation simply prevents rates from falling for longer than expected?
That matters because a mortgage does not need another dramatic cash-rate increase to remain expensive.
A longer period of restrictive interest rates can itself create significant household pressure.
The US 10-Year Treasury Yield Has Moved Above 5%
Oil is only half of today's global-market story.
The benchmark US 10-year Treasury yield has also climbed above 5%.
Reuters reported the yield reached approximately 5.004%, its highest level since 2007, as investors responded to stronger inflation concerns, elevated oil prices and expectations that US monetary policy could remain restrictive. (Reuters)
Global government bond yields have risen more broadly as well.
Reuters reported that average G7 government bond yields have climbed to levels not seen since the global financial crisis period. (Reuters)
Why should an Australian homeowner care about a US government bond?
Because global interest-rate markets are interconnected.
US Treasury yields influence global financial pricing, investor expectations and the cost of capital.
Australian bond yields and swap markets can move in the same direction when global inflation or monetary-policy expectations change.
Those markets matter to banks.
Mortgage Rates Begin With the Cost of Money
Banks do not simply create mortgage funding at zero cost.
They need to obtain money before lending it.
The RBA explains that roughly two-thirds of major Australian bank funding comes from deposits, while almost one-third comes from debt funding such as bonds and other wholesale-market instruments. Equity provides the remainder. (Reserve Bank of Australia)
Banks therefore pay interest to savers.
They pay interest on term deposits.
They issue bonds.
They borrow in wholesale markets.
They hedge foreign-currency funding.
They manage interest-rate risk through swaps.
All of those activities have costs.
Those costs help determine what banks can sustainably charge borrowers.
The RBA Cash Rate Still Matters Enormously
None of this means the cash rate is unimportant.
It remains one of the strongest influences on Australian bank funding costs and variable mortgage pricing.
The RBA says changes in the cash rate typically pass through almost fully to major banks' overall funding costs over time. (Reserve Bank of Australia)
Short-term Australian wholesale rates such as the Bank Bill Swap Rate, or BBSW, are also strongly influenced by expectations for the cash rate.
That means markets can begin repricing before an RBA meeting actually occurs.
If investors become convinced that the RBA will raise rates in the future, short-term funding markets may move ahead of the official announcement.
This is one reason mortgage pricing can sometimes change between RBA meetings.
Bank Funding Costs Have Already Increased in 2026
The RBA's August Statement on Monetary Policy provides useful context.
Since its May Statement, estimated funding costs for major Australian banks increased by approximately 18 basis points as higher interest rates flowed through to deposit and wholesale-debt costs. (Reserve Bank of Australia)
Variable mortgage rates had increased by nearly 75 basis points between January and June.
However, some lenders subsequently reduced selected advertised variable mortgage rates by around 20 to 30 basis points because competition for borrowers remained strong. (Reserve Bank of Australia)
That combination perfectly demonstrates why mortgage pricing is more complicated than simply following the RBA.
Funding costs pushed upward.
But competition pushed some mortgage offers downward.
Both forces can exist at the same time.
Competition Can Override Part of the Funding Pressure
Imagine two lenders experiencing similar wholesale-market conditions.
One lender aggressively wants to increase its mortgage market share.
The other is comfortable with its current lending volumes.
The first lender may accept a smaller profit margin and offer sharper mortgage pricing.
The second may not.
That is why two banks can respond differently to exactly the same RBA decision.
The RBA says lending spreads remain relatively low compared with pre-pandemic levels, partly because competition among lenders remains strong. (Reserve Bank of Australia)
This is particularly important for mortgage holders.
A difficult global market does not necessarily mean every lender will raise every mortgage rate immediately.
The actual outcome depends partly on competition and each lender's funding position.
Fixed Mortgage Rates Can Behave Differently From Variable Rates
This distinction is especially important.
Variable mortgages are heavily influenced by the cash rate and short-term funding conditions.
Fixed mortgage rates are more directly influenced by expectations about future interest rates.
The RBA says new fixed mortgage rates generally move with corresponding swap rates.
Fixed rates declined through much of 2025, then began increasing around the end of the year as swap rates moved higher. (Reserve Bank of Australia)
This helps explain something borrowers sometimes find confusing.
The RBA can leave the cash rate unchanged while banks increase fixed mortgage rates.
Or fixed rates can decline before the RBA cuts the cash rate.
That happens because markets are pricing the future.
Bond Yields and Swap Rates Are Not the Same Thing
It is worth making one technical distinction.
Australian mortgage rates are not directly priced from the US 10-year Treasury yield.
A bank does not simply see the US Treasury at 5% and add a margin to calculate your home loan.
Australian mortgage pricing relies much more directly on Australian deposit costs, BBSW, bank bond yields, swap rates, hedging costs and the lender's own pricing strategy.
But global bond markets matter because they influence financial conditions, inflation expectations and the price investors demand for lending money over longer periods.
So the US 10-year yield is better thought of as a global financial pressure signal rather than a direct mortgage-pricing formula.
The Australian Bond Market Has Already Felt Global Pressure
The current move is not occurring in isolation.
Earlier this year, the RBA noted that Australia's long-term nominal and real government bond yields had risen to around their highest levels since 2011 as monetary-policy expectations and global financial conditions tightened. (Reserve Bank of Australia)
Global oil disruption was specifically cited as one contributor to higher expectations for policy rates internationally.
That means the transmission mechanism is already visible:
higher energy prices can increase inflation expectations,
higher inflation expectations can push rate expectations upward,
higher rate expectations can lift bond and swap yields,
and those market rates can affect bank funding and lending costs.
The Four Forces Behind Your Mortgage Rate
A useful way to think about mortgage pricing is not one number, but four broad forces.
Mortgage pricing influence | Why it matters |
|---|---|
RBA cash rate | Heavily influences short-term bank funding and variable lending rates |
Wholesale markets | BBSW, swap rates and bank bond yields affect bank funding costs |
Global conditions | Oil, bond yields, inflation expectations and financial volatility influence market pricing |
Lender competition | Banks may accept smaller margins to attract or retain borrowers |
The rate eventually offered to an individual borrower is then also influenced by factors such as loan size, loan-to-value ratio, owner-occupier versus investor status, repayment type and lender policy.
So even borrowers with the same property value can receive different mortgage rates.
What Are Australian Mortgage Rates Currently Doing?
RBA lending data for July 2026 shows the average owner-occupier mortgage rate across outstanding loans was 6.21%.
For principal-and-interest owner-occupier loans, the average outstanding rate was 6.19%.
The average rate on new principal-and-interest owner-occupier loans was slightly lower at 6.16%. (Reserve Bank of Australia)
Investor mortgage rates were higher.
The average outstanding investor mortgage rate was 6.44%, while new investor loans averaged 6.41%.
These are market averages.
Individual borrowers may be paying substantially more or less depending on their lender and loan structure.
That is why knowing the average is useful, but checking your actual mortgage is more important.
Global Markets Can Affect Fixed Rates Before Variable Rates
If global bond yields remain elevated, borrowers may first notice the impact through fixed-rate pricing.
That is because fixed mortgages reference expectations for interest rates over future periods.
Suppose markets suddenly believe inflation will remain high for another three years.
Swap rates for corresponding terms may increase.
A lender offering three-year fixed mortgages may therefore adjust pricing even if the RBA has not changed today's overnight cash rate.
This is one reason borrowers considering fixed versus variable rates should not assume that today's RBA decision completely determines tomorrow's fixed-rate offers.
Currency Movements Can Add Another Layer
Higher US bond yields can also strengthen the US dollar.
Reuters reported the Australian dollar weakening as the US dollar benefited from rising Treasury yields and global risk aversion. (Reuters)
A weaker Australian dollar can make imported goods and internationally priced commodities more expensive locally.
Oil is particularly important because it is priced internationally in US dollars.
This means Australian consumers can theoretically face pressure from both:
higher global oil prices,
and a weaker Australian dollar.
That combination can amplify imported inflation.
Again, the relationship is not automatic, but it is another reason global financial conditions matter to Australian monetary policy.
Oil Can Affect Mortgage Borrowers Before Their Rate Changes
There is another connection that is even more immediate.
Suppose your mortgage rate does not change at all.
Higher oil prices could still increase:
petrol costs,
delivery costs,
airfares,
business transport costs,
and eventually prices for some goods and services.
The RBA estimates fuel makes up around 3.3% of Australia's CPI basket and also contributes indirectly to approximately 2% to 2.5% of the domestic cost of producing and distributing other goods and services. (Reserve Bank of Australia)
So a household can experience greater mortgage stress without the mortgage repayment itself changing.
If petrol, groceries and transport become more expensive, less income remains available after the home-loan payment.
The Next RBA Meeting Is Important, But It Is Not the Whole Story
The RBA will announce its next cash-rate decision at 2:30 pm on 29 September 2026.
The current cash-rate target is 4.35%. (Reserve Bank of Australia)
Mortgage holders should watch that meeting.
But they should also monitor what lenders are doing between meetings.
As we have seen recently, some Australian lenders have reduced selected mortgage rates even while the cash rate remained high and bank funding costs increased.
Competition matters.
Funding markets matter.
Bond yields matter.
Inflation expectations matter.
Global energy markets matter.
The RBA remains central to the story, but it is not the entire story.
Why This Matters When Comparing Home Loans
This environment reinforces why mortgage comparison should focus on what is available now rather than simply waiting for future RBA announcements.
One lender may have relatively cheap funding.
Another may aggressively want new customers.
Another may favour low-LVR borrowers.
Another may offer sharper pricing to refinance customers.
Mortgage markets can therefore contain meaningful pricing differences even when all lenders operate under the same cash rate.
This is especially relevant for borrowers whose existing lender has not reviewed their rate recently.
A Mortgage Rate Can Change Without the RBA Moving
Borrowers should remember this simple principle.
The RBA sets the Australian cash-rate target.
It does not directly set every home-loan rate.
Australian lenders determine their own mortgage pricing based on their funding costs, market conditions, risk, competition and commercial strategy.
That is why mortgage rates can:
increase before an RBA hike,
fall before an RBA cut,
remain unchanged after an RBA decision,
or move differently across competing banks.
The relationship is strong, but it is not mechanical.
Waiting for the RBA Can Mean Ignoring Today's Market
A homeowner might think:
"I'll review my mortgage once rates come down."
But mortgage markets are already moving.
Fixed rates can change.
New-customer discounts can appear.
Banks can negotiate retention pricing.
Funding conditions can improve or deteriorate.
Waiting for a specific RBA decision therefore may not always be necessary.
You can review today's mortgage against today's market.
The Bigger Lesson: Your Mortgage Is Connected to the Global Financial System
It is easy to think of an Australian mortgage as a purely domestic financial product.
In reality, it sits inside an interconnected global system.
Conflict in the Middle East can move oil.
Oil can influence inflation.
Inflation can move global bond markets.
Bond markets affect interest-rate expectations.
Those expectations influence swap markets and bank funding.
Banks then combine those funding costs with competition, risk and commercial strategy to determine mortgage pricing.
That is why the current combination of Brent above US$100 and the US 10-year Treasury yield around 5% deserves attention from Australian borrowers.
Neither number directly determines your mortgage rate.
But both provide important information about the financial environment in which Australian lenders are operating.
Your Mortgage Rate Isn't Controlled by Just One Number
The cash rate matters.
But it is only part of the equation.
Today's mortgage pricing also reflects wholesale funding markets, global bond yields, inflation expectations, lender competition and each bank's individual funding strategy.
For Australian borrowers, the practical takeaway is straightforward.
Do not assume your mortgage will only change when the RBA moves.
And do not assume you need to wait for the next RBA meeting before checking whether your current loan is competitive.
Is Your Current Home Loan Still Competitive?
At Loan & Own Mortgages, we help Australian homeowners understand how their existing mortgage compares with current lender options.
A home-loan review can look at your current rate, loan structure, equity position, lender pricing and available alternatives.
Sometimes refinancing may produce a better outcome.
Sometimes negotiating with the existing lender may make more sense.
And sometimes the current mortgage is already competitive.
The important thing is knowing where you stand.
Speak with Loan & Own Mortgages to review your home loan before assuming the RBA is the only number that matters.
Data sources
Reuters, 15 September 2026: Brent crude traded around US$108.20 as renewed attacks on Saudi energy infrastructure increased concerns about global oil supply. (Reuters)
Reuters, 15 September 2026: The benchmark US 10-year Treasury yield moved above 5%, reaching its highest level since 2007 as oil, inflation and rate expectations pushed global bond yields higher. (Reuters)
Reserve Bank of Australia: The Australian cash-rate target is 4.35%, with the next monetary-policy update scheduled for 29 September 2026. (Reserve Bank of Australia)
Reserve Bank of Australia, August 2026 Statement on Monetary Policy: Major-bank funding costs increased approximately 18 basis points since May, while selected lenders cut advertised variable mortgage rates by 20 to 30 basis points amid continued competition. (Reserve Bank of Australia)
Reserve Bank of Australia, May 2026 Bulletin: Deposits account for roughly two-thirds of major-bank funding and debt almost one-third. Wholesale debt costs, BBSW, swaps and hedging all contribute to the cost of funding Australian lending. (Reserve Bank of Australia)
Reserve Bank of Australia, July 2026 lending data: Average outstanding owner-occupier housing rates were 6.21%, with new principal-and-interest owner-occupier loans averaging 6.16%. (Reserve Bank of Australia)
Reserve Bank of Australia, May 2026 Statement on Monetary Policy: Global crude accounts for approximately 40% of Australian retail fuel prices, while a 10% domestic fuel-price rise could directly add a little over 0.3 percentage points to headline inflation over one to two quarters. (Reserve Bank of Australia)
This article provides general information only and does not constitute personal financial, credit, investment, tax or legal advice. Mortgage rates, funding costs, lender policies and refinancing eligibility can change and depend on individual circumstances.
