Some Mortgage Rates Are Rising While Others Are Falling: What Borrowers Need to Know
Some Mortgage Rates Are Rising. Others Are Falling. And Some Borrowers Can Now Avoid LMI at 90% LVR.
Australia is days away from another Reserve Bank interest-rate decision.
The cash-rate target remains 4.35%, with the RBA's Monetary Policy Board meeting on 28 and 29 September and its decision due at 2:30 pm on 29 September. (Reserve Bank of Australia)
With markets focused intensely on what the RBA might do next, it would be easy to assume every mortgage lender is simply waiting to move in the same direction.
But the lending market is telling a more complicated story.
This week:
Ubank increased fixed mortgage rates by approximately 25 to 30 basis points.
ING increased some owner-occupier variable rates by 5 basis points.
At the same time, ING reduced certain higher-LVR owner-occupier rates by 5 basis points and higher-LVR investor rates by 10 basis points.
Bankwest expanded access to its professional LMI waiver.
Bank of Sydney is offering eligible professionals lending above 80% and up to 90% LVR without lenders mortgage insurance on qualifying owner-occupied loans. (Broker Daily)
All of these changes are occurring under exactly the same RBA cash rate.
That tells borrowers something important:
The RBA influences mortgage pricing, but it does not determine every individual home-loan rate or lending policy.
What Changed This Week?
Here is the lending-market snapshot.
Lender | Change | What it means |
|---|---|---|
Ubank | Fixed rates +25 to +30 bps | Fixing has become more expensive across several borrower categories |
ING owner-occupier ≤80% LVR | Variable rates +5 bps | Lower-LVR owner-occupiers pay slightly more |
ING owner-occupier >80% LVR | Selected rates -5 bps | Some higher-LVR borrowers received a cut |
ING investor 80.01%-90% LVR | -10 bps | Selected higher-LVR investor pricing improved |
Bankwest | Expanded LMI-waiver eligibility | More professional and PAYG borrower groups may qualify |
Bank of Sydney | LMI-free lending available up to 90% LVR for eligible professionals | Selected borrowers may avoid an otherwise significant upfront borrowing cost |
Broker Daily reported these changes across 18 to 25 September. (Broker Daily)
This is not what a simple "rates are going up" market looks like.
It is a market where lenders are actively choosing which borrowers they want.
Ubank Has Increased Fixed Mortgage Rates
Ubank increased fixed home-loan pricing effective 24 September.
Owner-occupier principal-and-interest fixed rates increased by approximately 25 to 30 basis points.
Investor principal-and-interest fixed rates also increased by 25 to 30 basis points.
Interest-only fixed pricing for eligible loans at 80% LVR or below increased by around 25 basis points. (Broker Daily)
Ubank's published fixed-rate range now starts around 6.49% for some lower-LVR owner-occupier products, with rates increasing depending on fixed term and borrower profile. (uBank)
That is significant because fixed mortgage rates often move before an RBA decision.
Why Can Fixed Rates Move Before the RBA?
A fixed mortgage is priced partly around expectations for future interest rates and funding conditions.
If wholesale markets begin expecting higher interest rates over the coming one, two or three years, lenders can adjust fixed pricing before the RBA actually changes the overnight cash rate.
That is why borrowers sometimes see:
fixed rates rise while the cash rate is unchanged,
or fixed rates fall before the RBA starts cutting.
The RBA cash rate remains important.
But fixed-rate pricing is also forward-looking.
Ubank's move therefore provides another example of mortgage markets adjusting ahead of the central-bank decision.
ING Did Something Much More Interesting
ING's changes show why borrowers should avoid thinking about mortgage pricing as one single market.
Effective 23 September, ING increased owner-occupier principal-and-interest variable rates by 5 basis points for LVR bands up to 80%.
But instead of increasing every rate, it went the other way for several higher-LVR borrowers.
Selected Orange Advantage owner-occupier P&I loans above 80% LVR fell by 5 basis points.
Investor principal-and-interest and interest-only rates between 80.01% and 90% LVR fell by 10 basis points. (Broker Daily)
So within one lender:
some borrowers became more expensive to lend to,
while others received better pricing.
That is a powerful reminder that lenders price borrower segments differently.
Why Would a Lender Cut Higher-LVR Rates?
At first glance, this can look strange.
A borrower with a 90% LVR generally represents more credit risk than someone with a 60% LVR.
So why would ING cut rates for some higher-LVR loans while increasing them for borrowers with more equity?
Because mortgage pricing is not determined by risk alone.
Lenders also consider:
portfolio mix,
customer-acquisition targets,
competition,
funding costs,
expected profitability,
risk concentration,
and which types of customers they currently want more of.
ING said it regularly reviews pricing according to changing market conditions and developments in domestic and global markets. (Broker Daily)
A lender can therefore decide that one segment needs sharper pricing to attract more applications while another segment does not.
Your LVR Can Change the Rate You Are Offered
Loan-to-value ratio, or LVR, compares how much you are borrowing with the value of the property.
For example:
Property value: $800,000
Mortgage: $640,000
LVR:
80%
If the mortgage were $720,000 instead, the LVR would be:
90%
Many Australian lenders divide mortgage pricing into LVR bands.
That means a borrower at 60% LVR can potentially receive different pricing from someone at 85% LVR even if:
they earn the same income,
buy the same type of property,
and use the same lender.
Ubank's current rate tables explicitly demonstrate this, with pricing varying according to LVR. (uBank)
LVR Can Affect Much More Than the Interest Rate
LVR can influence:
interest-rate pricing,
lender eligibility,
borrowing limits,
credit assessment,
refinance options,
and whether lenders mortgage insurance applies.
That makes equity one of the most important variables in mortgage strategy.
A household with substantial equity may have access to a completely different group of products from a borrower entering the market with a 10% deposit.
But this week's lender changes reveal an important exception.
Some professions can sometimes access high-LVR lending without paying LMI.
What Is Lenders Mortgage Insurance?
Lenders mortgage insurance, usually called LMI, protects the lender if the borrower cannot repay the mortgage.
It does not insure the homeowner.
MoneySmart explains that LMI is commonly payable when the amount borrowed exceeds 80% of the property's value. It is generally charged as a one-off cost and may either be paid at settlement or added to the mortgage. (Moneysmart)
That 80% threshold is why many buyers aim for a 20% deposit.
But it is not a universal rule.
Some borrowers can buy with smaller deposits.
And some lenders waive LMI for selected professional groups.
Bank of Sydney Is Offering LMI-Free Lending Up to 90% LVR
Bank of Sydney has expanded an option that could be particularly valuable to qualifying professional borrowers.
Its current broker rate table includes owner-occupied principal-and-interest lending above 80% and up to 90% LVR where LMI is waived for eligible professionals. (Bank of Sydney)
Its published Basic Home Loan pricing currently shows:
up to 80% LVR: 6.19% p.a.
above 80% to 90% LVR with the professional LMI waiver: 6.89% p.a.
Those figures can change and individual eligibility criteria apply. (Bank of Sydney)
So the waiver does not mean the higher-LVR loan receives the same rate as a 60% or 80% LVR borrower.
What it can potentially remove is the separate LMI expense.
Who Can Qualify?
Bank of Sydney's current public broker material lists professional categories that may qualify including:
medical professionals,
registered accountants,
financial analysts and actuaries,
registered solicitors and barristers,
registered engineers,
and commercial pilots. (Bank of Sydney)
Broker Daily separately reported a broader group of eligible professions under Bank of Sydney's updated policy, including selected education, emergency-services, construction, property and science occupations. (Broker Daily)
Because eligibility policies can change and public product pages do not always update simultaneously, borrowers should have the specific profession and application scenario checked before relying on a waiver.
Bankwest Has Also Expanded Its Professional LMI Waiver
Bankwest has expanded its LMI-waiver eligibility to additional PAYG groups.
Broker Daily reports the expansion includes:
lawyers,
accountants,
selected professional employees,
managerial federal-government employees at APS6, EL1, EL2 and SES levels,
employees of selected banks,
and employees of selected large technology companies. (Broker Daily)
The policy does not apply universally.
Broker Daily says restrictions remain around factors including interest-only lending, self-employed income, foreign income, selected property types and certain other application structures. (Broker Daily)
That qualification is important.
"LMI waiver available" does not mean everyone working in a listed occupation automatically qualifies.
Why an LMI Waiver Can Matter
Imagine someone wants to buy an $800,000 property with a 10% deposit.
Deposit:
$80,000
Mortgage before other purchase costs:
$720,000
LVR:
90%
Ordinarily, a loan at that LVR may require LMI.
MoneySmart says LMI is commonly payable above 80% LVR and can increase the upfront cost of entering a mortgage. (Moneysmart)
If the borrower qualifies for a professional LMI waiver, that cost may potentially be avoided.
That can have several benefits.
The buyer may not need to wait as long to accumulate a 20% deposit.
They may preserve more savings after settlement.
They may avoid capitalising LMI into the mortgage.
But that does not automatically make borrowing at 90% LVR appropriate.
Avoiding LMI Does Not Remove the Risks of a Small Deposit
This distinction matters.
If you borrow 90% of a property's value without paying LMI, you still have a 90% LVR mortgage.
That means you begin with relatively little equity.
If the property falls in value, your LVR can increase quickly.
For example:
Purchase price: $800,000
Loan: $720,000
Starting LVR: 90%
If the property were later valued at $760,000 while the loan remained close to $720,000:
LVR would increase to approximately 94.7%.
That could make refinancing considerably harder.
So an LMI waiver reduces one cost.
It does not eliminate high-LVR risk.
This Is Why "No LMI" Should Not Be the Only Decision Factor
A mortgage should still be assessed on:
interest rate,
comparison rate,
monthly repayment,
loan features,
deposit remaining after settlement,
cash reserves,
property risk,
repayment buffer,
and long-term affordability.
Someone may save money by avoiding LMI but pay a higher interest rate.
Another borrower might choose to continue saving and access a lower-LVR product later.
Neither strategy is automatically better.
It depends on the numbers.
Some Borrowers May Be Better Off at 80% LVR Even if 90% Is Available
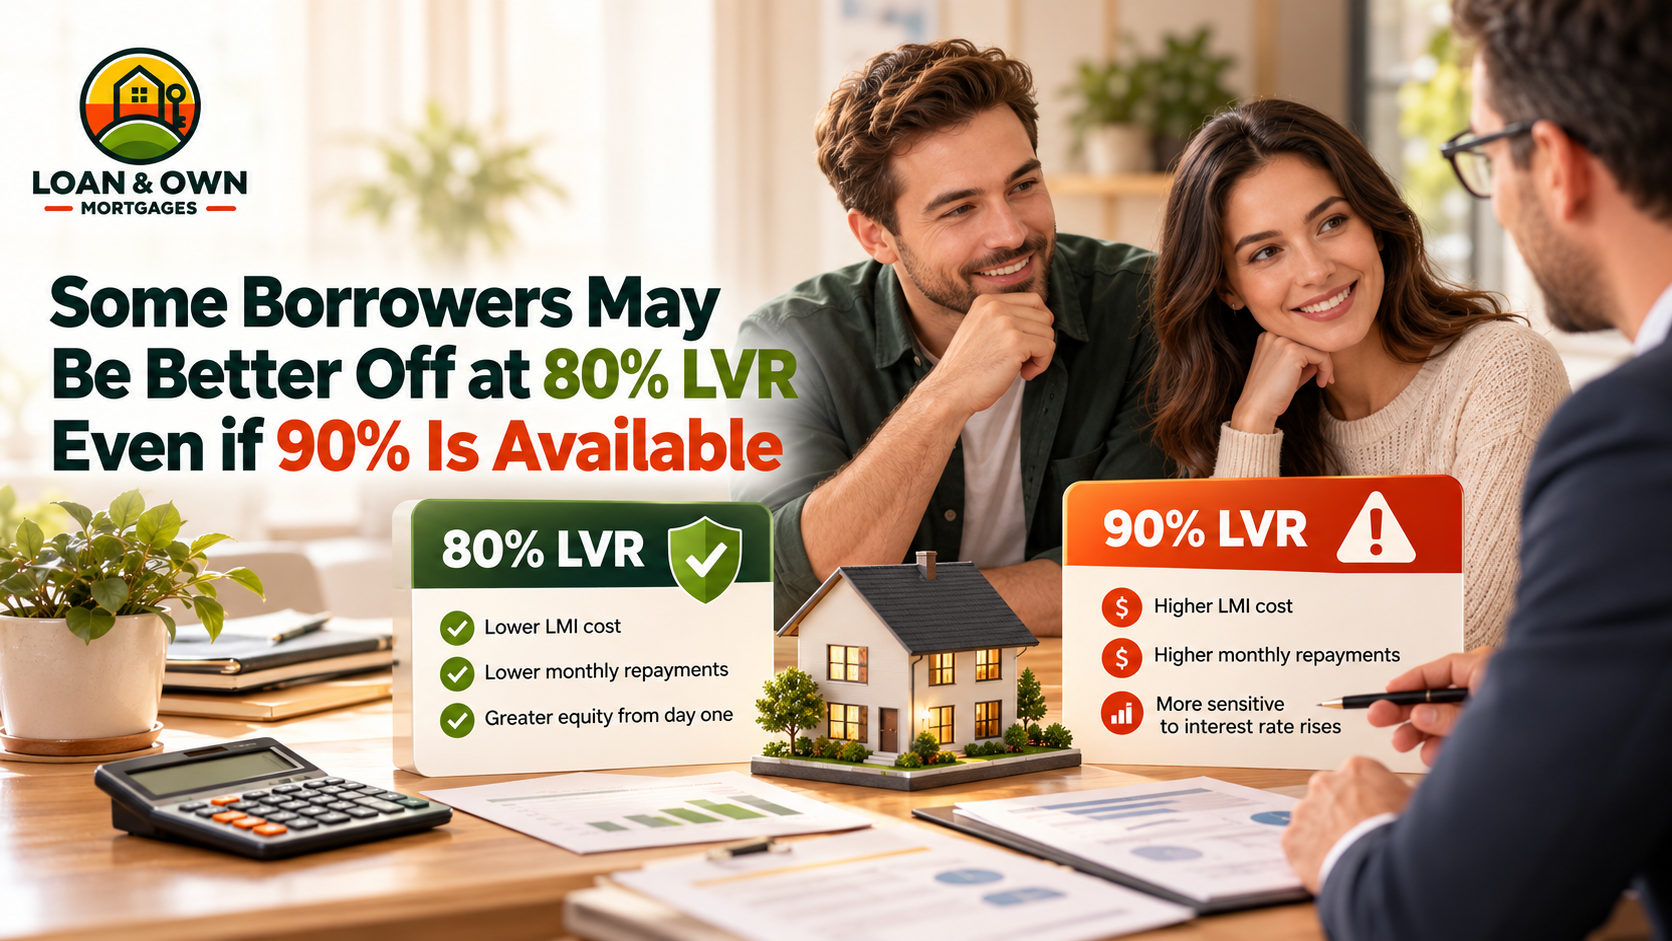
The ability to borrow at 90% does not mean a borrower should necessarily do so.
Look at Bank of Sydney's published pricing.
Its BOS Basic Home Loan currently lists 6.19% p.a. for loans up to 80% LVR versus 6.89% p.a. for professional-waiver loans above 80% and up to 90% LVR. (Bank of Sydney)
That is a substantial rate difference.
Whether buying earlier outweighs the higher ongoing interest cost depends on:
property price,
deposit size,
time needed to save more,
future property-price movements,
interest rates,
and individual financial circumstances.
This is why the calculation should not stop at:
"Can I avoid LMI?"
The better question is:
"What is the overall cost and benefit of buying at this LVR?"
Fixed Rates and Variable Rates Are Sending Different Signals
Another interesting feature of the current market is the divergence between fixed and variable pricing.
Ubank has raised fixed rates.
ING has adjusted variable products in both directions.
That is not necessarily contradictory.
Fixed and variable loans respond to different combinations of factors.
Variable rates tend to be strongly influenced by:
the RBA cash rate,
short-term funding,
lender pricing strategy,
and competition.
Fixed rates depend more heavily on expectations for future funding and interest-rate conditions.
So borrowers should not expect both markets to move together every week.
The RBA Does Not Set Your Mortgage Rate
The Reserve Bank itself explains that the cash rate influences other interest rates, including mortgage rates. (Reserve Bank of Australia)
The key word is:
influences.
The RBA does not tell Ubank what rate to charge a 90% LVR investor.
It does not tell ING whether to cut a particular investor product by 10 basis points.
It does not determine whether Bank of Sydney waives LMI for an engineer.
Those decisions belong to the lender.
That is why mortgage shopping remains relevant even when the direction of monetary policy appears obvious.
Lenders Have Different Appetites at Different Times
One bank might aggressively pursue:
first-home buyers.
Another may want:
professional borrowers.
Another:
investors.
Another:
low-LVR refinancers.
Another:
self-employed applicants.
These preferences can change.
That means a lender that was highly competitive for your situation six months ago may not be the strongest option today.
Likewise, a lender you previously ignored may suddenly become competitive because it changes policy.
That is exactly what this week's changes illustrate.
Your Occupation Can Affect Your Mortgage Options
Borrowers often assume lenders only care about:
income,
credit history,
and deposit.
Occupation can also matter.
Some lenders offer specialised policies for professions viewed as having:
stable income,
strong future earning potential,
lower default risk,
or particular employment characteristics.
Medical professionals are the most familiar example.
But professional waivers now extend across a much wider group of occupations at selected lenders.
That can materially alter the deposit required to avoid LMI.
Investors Should Pay Particular Attention to LVR Bands
ING's change is especially relevant for investors.
The lender reduced selected investor P&I and interest-only variable rates by 10 basis points for LVRs between 80.01% and 90%. (Broker Daily)
That is unusual enough to demonstrate why investors should not assume:
lower LVR always equals the sharpest new pricing change,
or every investor rate rises when the RBA outlook becomes more hawkish.
Lender pricing is portfolio-specific.
The Difference Between 80% and 81% Can Be Surprisingly Important
Mortgage policy frequently contains sharp thresholds.
79.9% LVR may qualify for one rate.
80.1% may fall into another category.
90.1% may move into another.
That means small changes in:
property valuation,
loan size,
deposit,
or cash contribution
can sometimes alter the available product materially.
For buyers close to an LVR threshold, adjusting the loan amount slightly may potentially improve pricing or remove an insurance requirement.
This should always be assessed against the borrower's cash reserves and broader financial position.
Property Valuation Matters More Than Many Borrowers Realise
LVR is based on the value accepted by the lender.
That does not always equal:
the owner's estimate,
the real-estate agent's estimate,
or even the original purchase price.
If a lender values a property lower than expected, the calculated LVR increases.
That can affect:
interest-rate tier,
LMI,
refinancing eligibility,
or loan approval.
This becomes particularly important in a falling property market.
A borrower who believed they had an 80% LVR may discover a new lender calculates 84%.
The product options can suddenly change.
Refinancers Need to Watch LMI Too
LMI is not only a first-home-buyer issue.
MoneySmart warns that homeowners refinancing with less than 20% equity may need to pay LMI again, and that the cost can outweigh savings from moving to a lower interest rate. (Moneysmart)
That is highly relevant in today's market.
Borrowers may see an attractive refinance rate advertised.
But if their property has declined in value and the resulting LVR is above 80%, the economics of switching may be very different.
Again:
the headline interest rate is only one variable.
The Next RBA Decision Still Matters
None of this means borrowers should ignore the RBA.
The cash-rate target remains 4.35%.
The next decision is due on 29 September. (Reserve Bank of Australia)
A change in the cash rate could affect variable home-loan pricing across the market.
But today's lender behaviour already shows that even before the decision:
different products,
different LVRs,
different professions,
and different lending purposes
can receive very different treatment.
What Should Borrowers Compare Right Now?
A useful mortgage comparison should look at at least:
your current interest rate,
comparison rate,
LVR,
property valuation,
loan purpose,
owner-occupied versus investment,
principal-and-interest versus interest-only,
fixed versus variable,
offset and redraw features,
LMI requirements,
professional waivers,
application and ongoing fees,
and lender eligibility rules.
That is much more useful than simply asking:
"Which bank has the lowest rate?"
First-Home Buyers Should Check Whether Their Profession Changes the Equation
Someone saving toward a 20% deposit may discover they qualify for:
a professional LMI waiver,
a government guarantee,
or another lender structure allowing them to purchase with a smaller deposit.
That does not mean buying immediately is automatically right.
But the borrower should at least know the option exists.
Otherwise they could spend several additional years saving toward a target that was never strictly required.
Existing Homeowners Should Review Their LVR Before Refinancing
Before switching lenders, calculate approximately:
property value,
mortgage balance,
and resulting LVR.
Then identify whether the target lender's best advertised rate actually applies to that LVR.
A rate advertised "from 5.99%" may only apply below a particular threshold.
The borrower's actual rate could be materially different.
Professional Borrowers Should Not Assume Every Waiver Is the Same
Professional-LMI policies vary significantly.
One lender may allow 90% LVR.
Another may cap at a different level.
Some allow investment loans.
Others only allow owner-occupied purchases.
Some require minimum professional experience.
Others may restrict certain employment structures.
Bank of Sydney's lending guidelines, for example, say its professional waiver may be approved by exception up to 90% LVR and includes specific income and professional-experience requirements. (Bank of Sydney)
This is where policy comparison becomes just as important as rate comparison.
The Bigger Lesson: Mortgage Pricing Is Becoming More Segmented
The most interesting story this week is not simply that rates moved.
It is how selectively they moved.
Ubank:
fixed rates up.
ING:
some variable rates up, others down.
Bankwest:
professional-waiver access expanded.
Bank of Sydney:
eligible professionals can borrow above the traditional 80% threshold without LMI under selected products.
That means borrowers increasingly need to think about their personal lending profile rather than the broad market alone. (Broker Daily)
Two people can walk into the same mortgage market on the same day and receive very different outcomes.
Your Best Mortgage Option May Depend More on Your Profile Than the Headline Rate
The questions lenders are effectively asking include:
How much equity do you have?
Are you buying or refinancing?
Will you live in the property?
Are you investing?
What is your profession?
How stable is your income?
Are repayments principal and interest?
What is the property's location and type?
What percentage of its value are you borrowing?
Those answers determine what part of the lender's policy and pricing matrix applies to you.
That is why mortgage comparison becomes more valuable when lender policies diverge.
Are You Looking at the Rate or the Whole Lending Strategy?
At Loan & Own Mortgages, we help home buyers, homeowners, investors and professional borrowers compare more than headline interest rates.
That can include reviewing:
your LVR,
available rates,
potential LMI,
professional waivers,
loan structure,
lender policy,
refinancing options,
and the overall cost of borrowing.
Some mortgage rates are rising.
Others are falling.
And for some borrowers, the biggest saving may not come from the interest rate at all.
It may come from qualifying for a different lending policy.
Speak with Loan & Own Mortgages to understand which lenders and structures fit your circumstances.
Data sources
Broker Daily, 25 September 2026: Ubank increased fixed rates by 25 to 30 basis points, ING made different variable-rate changes according to LVR and borrower type, while Bankwest and Bank of Sydney expanded LMI-waiver policies for eligible professional borrowers. (Broker Daily)
Broker Daily, 23 September 2026: ING increased owner-occupier P&I variable rates by 5 basis points for LVRs up to 80%, cut selected owner-occupier rates above 80% by 5 basis points and cut selected investor rates between 80.01% and 90% LVR by 10 basis points. (Broker Daily)
Ubank: Current published fixed-rate tables show pricing varying materially by loan purpose, repayment type, fixed term and LVR. (uBank)
Bank of Sydney: Current broker pricing includes owner-occupied loans above 80% and up to 90% LVR with LMI waived for eligible professionals, subject to lending criteria and professional eligibility. (Bank of Sydney)
MoneySmart: LMI generally applies when borrowing exceeds 80% of a property's value and protects the lender rather than the borrower. Refinancers with less than 20% equity may also face LMI when switching lenders. (Moneysmart)
Reserve Bank of Australia: The cash-rate target remains 4.35%, with the next monetary-policy decision due at 2:30 pm on 29 September 2026. (Reserve Bank of Australia)
This article provides general information only and does not constitute personal financial, credit, investment, tax or legal advice. Interest rates, LMI policies, professional waivers, valuations and lending criteria can change and depend on individual circumstances.
