What If the RBA Stops Hiking, But Mortgage Rates Still Don’t Fall?
What If the RBA Stops Hiking, But Mortgage Rates Still Don’t Fall?
Australian mortgage holders have spent much of 2026 watching one number:
the Reserve Bank cash rate.
After four increases this year, the RBA cash-rate target now stands at 4.60%, effective from 30 September. Its next monetary-policy decision is scheduled for 3 November. Reserve Bank of Australia
That makes one question increasingly important:
If the RBA eventually stops raising rates, does that automatically mean mortgage rates start falling?
Not necessarily.
A new source of pressure is emerging from global bond markets.
Government bond yields have surged across several major economies as investors respond to persistent inflation, higher energy prices, government borrowing and enormous capital requirements associated with global AI infrastructure investment.
Reuters reported that the world's largest sovereign bond markets experienced one of their worst months in years during September. US two-year Treasury yields rose almost 60 basis points during the month, while 10-year US yields moved above 5% for the first time since 2007. Australian two-year yields were also heading for their largest monthly increase since March. Reuters
And the pressure has not disappeared.
On 8 October, Britain's 10-year government borrowing cost climbed to 5.527%, its highest level since 2007, as Brent crude rose to around US$105 a barrel and global bond markets reacted to renewed inflation concerns. Reuters
For Australian mortgage borrowers, this matters because banks do not fund every home loan directly from the RBA cash market.
They obtain money from several places.
And when those sources become more expensive, mortgage pricing can come under pressure even without another RBA increase.
The Cash Rate Is Important, But It Is Not the Whole Mortgage Market
The RBA cash rate strongly influences Australian mortgage rates.
The Reserve Bank itself describes the cash rate as a key interest rate that influences lending and deposit rates throughout the economy. Reserve Bank of Australia
But influence is not the same as mechanically setting every mortgage rate.
Banks still determine their own:
variable rates,
fixed rates,
discounts,
new-customer pricing,
investor rates,
LVR tiers,
and refinancing offers.
They need to consider the cost of obtaining the money they lend.
That is where bond markets enter the story.
Where Do Australian Banks Get Their Money?
Australian banks fund their lending through several sources.
The RBA estimates that deposits account for roughly two-thirds of major-bank funding.
Debt markets account for almost one-third.
Equity makes up the remainder. Reserve Bank of Australia
That means customer savings accounts and term deposits are extremely important.
But so are wholesale debt markets.
Banks issue:
bonds,
bank bills,
and other debt securities
to obtain funding from institutional investors.
Some of that borrowing occurs in Australia.
Some occurs internationally.
If the cost of obtaining those funds rises, the economics of making a mortgage can change.
Wholesale Funding Costs Have Already Been Rising
The RBA reported in August that Australian major-bank funding costs had increased during 2026 as higher cash rates flowed through to deposit and wholesale debt rates.
Since its May Statement alone, estimated major-bank funding costs had risen another 18 basis points. Reserve Bank of Australia
The Reserve Bank's May analysis explains why.
Australian bank wholesale debt is heavily connected to market reference rates such as BBSW, while offshore debt is generally converted back into Australian-dollar exposures through foreign-exchange and cross-currency swaps. Reserve Bank of Australia
In other words, Australian banks operate inside global capital markets.
They are not isolated from what happens to US Treasuries, European government bonds, global swap rates or international investor demand.
What Does a Global Bond Sell-Off Actually Mean?
Bond prices and yields move in opposite directions.
When investors sell government bonds aggressively, bond prices fall and yields rise.
Those yields effectively become reference points for a huge range of financial products.
They influence:
corporate debt,
bank bonds,
business finance,
fixed mortgages,
and other long-term borrowing costs.
Reuters put the importance simply: sovereign bond markets matter because they affect loans to consumers and businesses, including mortgages. Reuters
That connection is already visible internationally.
Reuters reported on 1 October that the global bond sell-off was driving mortgage costs higher across several markets, including the UK, United States, euro area and Australia. Reuters
Australia's mortgage system works differently from Britain's or America's.
But the underlying lesson is relevant everywhere:
central-bank policy is not the only force determining the cost of credit.
Fixed Mortgage Rates Can React Before the RBA Does
This is especially important for fixed-rate borrowers.
Variable mortgage rates tend to respond strongly to the cash rate and bank funding costs.
Fixed rates are more sensitive to expectations about future interest rates and wholesale market pricing.
Suppose investors suddenly believe:
inflation will remain high,
oil will stay above US$100,
governments will issue more debt,
and central banks will need to keep rates elevated for longer.
Bond yields and swap rates can rise immediately.
A bank considering offering a three-year fixed mortgage therefore has to think about what funding may cost across that three-year period.
It does not need to wait for the RBA to raise rates again.
That is why fixed rates can move before the cash rate.
They can also move in the opposite direction if markets begin expecting future rate cuts.
The Global Market Is Suddenly Pricing “Higher for Longer” Again
The bond market's latest move reflects several pressures occurring at once.
Reuters identified persistent energy inflation, stronger-than-expected economic growth and large-scale technology investment as important factors behind the September sell-off.
US two-year Treasury yields recorded their sharpest monthly rise since early 2023.
Ten-year Treasury yields moved above 5%.
Bond-market volatility jumped almost 30% during September.
And major technology companies have issued more than US$200 billion of debt this year to finance AI infrastructure and related investment. Reuters
That creates competition for investor capital.
Governments want money.
Banks want money.
Technology companies want money.
Other corporations want money.
When the supply of debt becomes very large, investors can demand higher yields before they are willing to buy.
That can raise borrowing costs across the system.
Oil Is Making the Problem More Complicated
Energy is another important factor.
Reuters reported this week that Brent crude climbed around 5% to approximately US$105 a barrel amid renewed geopolitical and supply concerns. Reuters
Higher oil prices can feed into inflation through:
transport,
freight,
air travel,
manufacturing,
agriculture,
and distribution costs.
Bond investors care because stronger inflation reduces the real value of the fixed payments they receive.
They may therefore demand higher yields as compensation.
So a global oil shock can indirectly affect mortgage borrowers even if they never buy petrol themselves.
The chain can look something like this:
oil prices rise → inflation expectations rise → bond yields rise → wholesale funding becomes more expensive → mortgage pricing faces upward pressure.
It is not automatic.
But the connection exists.
Government Debt Is Competing for the Same Capital
Government borrowing is another part of the story.
Large sovereign bond issuance means investors have more securities to choose from.
France, the United States, Britain, Japan and several other major economies are all facing substantial financing requirements.
Reuters reported that investors are becoming more selective, rewarding governments seen as financially disciplined while demanding higher yields from countries with weaker fiscal positions. Reuters
Australian banks issuing bonds compete in those same global capital markets.
If international investors can earn attractive yields on highly liquid government bonds, banks may sometimes need to offer more attractive pricing on their own bonds to secure investor demand.
Again, the effect is indirect.
But it demonstrates why Australian mortgage rates cannot be understood by watching the RBA alone.
The RBA Could Hold Rates While Market Rates Still Rise
Imagine the RBA decides on 3 November to leave the cash rate unchanged at 4.60%.
That would mean:
no additional RBA increase.
But imagine at the same time:
US Treasury yields keep rising,
Australian bond yields rise,
BBSW remains elevated,
bank deposit competition increases,
and wholesale debt becomes more expensive.
A lender could still decide that some mortgage pricing needs to remain high.
It might:
increase a fixed rate,
reduce the size of a discount,
change pricing for a particular LVR tier,
or simply delay cutting variable rates.
There is nothing contradictory about that.
The RBA cash rate is one cost of money.
It is not the entire cost of money.
Banks Also Compete With Each Other
There is another force pulling in the opposite direction.
Competition.
Australian lenders have spent much of 2026 fighting aggressively for strong mortgage customers.
That competition can compress bank profit margins.
The RBA reported earlier this year that spreads between lending rates and the cash rate were around their narrowest levels in almost two decades, reflecting relatively low funding costs compared with the cash rate and strong lender competition. Reserve Bank of Australia
So even if global funding costs increase, banks might not immediately pass every increase onto borrowers.
A lender may accept a smaller margin to win customers.
Another may increase prices.
A third may target only low-LVR borrowers.
This is why the mortgage market can become fragmented.
Two Banks Can React Differently to the Same Bond Market
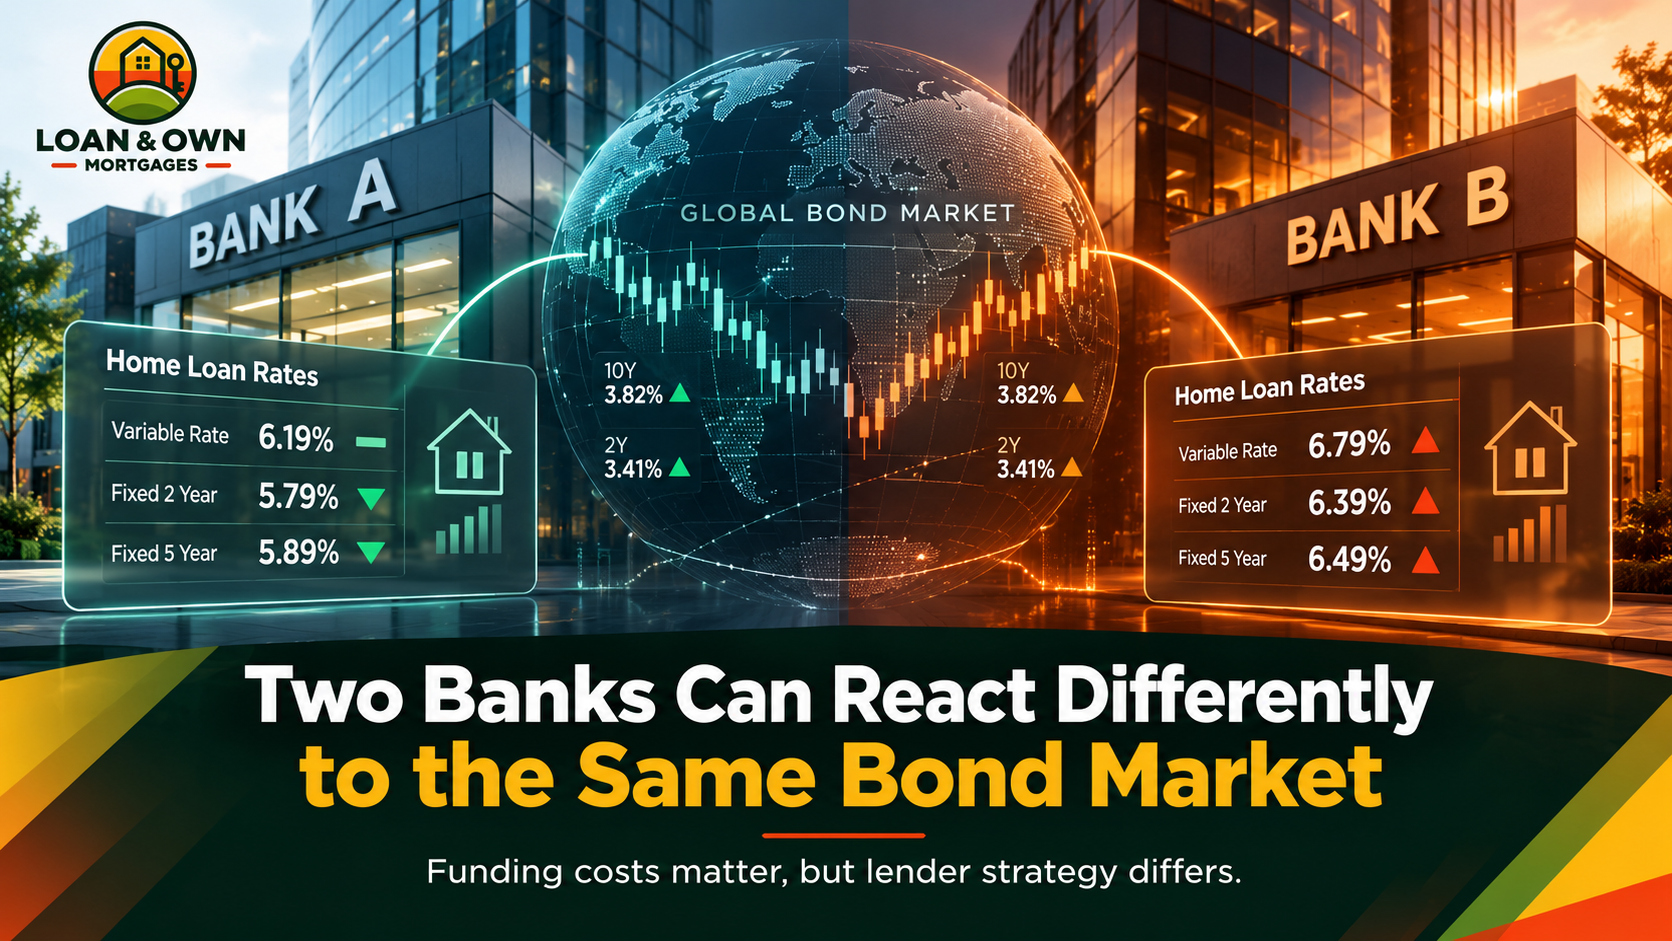
Suppose two Australian lenders both see global wholesale funding costs increase.
Bank A has a huge base of customer deposits.
Bank B depends more heavily on wholesale debt.
Bank A may be able to absorb the increase more easily.
Bank B may face stronger pressure to increase mortgage pricing.
Their hedging strategies may also differ.
Their customer mix may differ.
Their appetite for mortgage growth may differ.
Their capital position and profitability targets may differ.
So the global bond sell-off does not imply every Australian mortgage rate will increase by exactly the same amount.
It simply adds another factor lenders must price.
Variable Rates Are Not Immune Either
Global bond-market moves are often discussed in relation to fixed mortgages.
But variable borrowers should not assume they are completely insulated.
Variable rates are strongly influenced by the cash rate.
However, bank funding costs still matter.
The RBA's own research states that funding costs are a key determinant of the rates banks charge households and businesses. Reserve Bank of Australia
If higher wholesale costs persist long enough, lenders may respond through pricing decisions even if the RBA is holding steady.
That does not mean a lender will automatically raise its standard variable rate outside an RBA decision.
Competitive pressure may prevent it.
But it could appear through:
smaller discounts,
less aggressive refinance offers,
higher fixed rates,
different LVR pricing,
or reduced promotional offers.
A Cash-Rate Pause Is Not the Same as a Mortgage-Rate Cut
This distinction matters.
Three different situations can occur:
The RBA raises rates.
The RBA holds rates.
The RBA cuts rates.
A hold simply means the cash rate stays where it is.
It does not mean banks must reduce mortgage rates.
If the RBA holds at 4.60% in November, borrowers will still be operating in a relatively high-rate environment.
And if wholesale funding markets remain under pressure, lenders may have little incentive to begin aggressive rate reductions immediately.
Even an RBA Cut Might Not Be Passed Through Exactly
Eventually, the RBA may start reducing rates.
But borrowers should still not assume every lender will pass through every reduction in full.
Banks have to balance:
funding costs,
deposit pricing,
competition,
profit margins,
credit risk,
and customer acquisition.
A 0.25 percentage-point RBA cut could result in:
a full mortgage-rate reduction,
a partial reduction,
or different treatment across products.
Historically, pass-through can vary depending on market conditions.
That is why monitoring your actual loan matters more than assuming your bank will automatically deliver the best available rate.
Fixed Borrowers Need to Watch the Repricing Date
Someone currently locked into a fixed mortgage may feel insulated from today's volatility.
And during the fixed period, they generally are.
But the critical point is when the fixed period ends.
If global yields and fixed mortgage rates remain elevated when that happens, the borrower may face a much higher replacement rate than expected.
The relevant question is therefore not only:
"When will the RBA cut?"
It is:
"What rates will actually be available when my loan reprices?"
Those can be very different questions.
Bond Markets Can Change Quickly
One reason borrowers should be cautious about forecasts is that bond markets can move extremely quickly.
They respond to:
inflation releases,
employment data,
oil prices,
wars,
government budgets,
central-bank speeches,
bond issuance,
and investor sentiment.
The current sell-off demonstrates that point.
On 29 September, Reuters described global sovereign bonds as heading for one of their worst months in years. Reuters
A little over a week later, UK 10-year borrowing costs reached their highest level since 2007 as oil surged again. Reuters
Mortgage pricing can therefore change even between RBA meetings.
What Should Australian Mortgage Holders Watch?
Instead of focusing exclusively on one RBA number, borrowers can watch a broader set of signals:
The RBA cash rate and inflation outlook.
Australian government bond yields and BBSW.
Fixed mortgage rates, which can provide clues about market expectations.
New-customer variable rates and lender discounting.
Their own actual mortgage rate compared with what similar borrowers can access.
These indicators together provide a much better picture of the mortgage market than the cash rate alone.
Your Starting Rate Still Matters Most
Suppose the RBA does not raise rates again.
Borrower A is paying 5.95%.
Borrower B is paying 6.55%.
Even without any future cash-rate change, Borrower B may potentially have much more to gain from reviewing their mortgage.
Waiting for the RBA to cut rates can therefore become a distraction.
The relevant question is:
"Is my current mortgage competitive today?"
Not:
"When will the RBA rescue my repayment?"
Refinancing Still Depends on Equity and Serviceability
A lower rate somewhere else does not automatically mean every borrower can access it.
You still need to consider:
equity,
LVR,
income,
expenses,
existing debts,
property value,
and lender policy.
That matters particularly after recent declines in Australian property values.
A borrower may see an attractive refinance offer but discover that a lower valuation has pushed their LVR higher.
So rate comparison needs to happen together with an assessment of refinancing eligibility.
The Cheapest Rate Is Not Always the Best Loan
Global funding volatility also makes it important to compare the entire loan.
Consider:
annual fees,
offset features,
redraw,
fixed-rate break costs,
cashback conditions,
loan term,
repayment flexibility,
and refinancing expenses.
A mortgage with a slightly lower rate can still produce a worse financial outcome if the structure is unsuitable.
The objective is not to chase every tiny market move.
It is to maintain a mortgage structure that remains competitive and manageable.
The Bigger Lesson: The RBA Is Only One Part of the Mortgage Equation
Australia's cash rate currently sits at 4.60%. Reserve Bank of Australia
That matters enormously.
But Australian mortgage rates are shaped by a wider financial system.
Banks fund themselves through:
customer deposits,
domestic debt,
offshore debt,
and financial markets.
The RBA says those funding costs are a key determinant of lending rates. Reserve Bank of Australia
Right now, global bond markets are sending a warning.
Government yields are rising.
Energy prices remain volatile.
Inflation concerns have returned.
Governments and technology companies are issuing enormous amounts of debt.
And investors are demanding higher returns.
That means the end of an RBA hiking cycle would not automatically guarantee the beginning of a mortgage-rate cutting cycle.
What If the RBA Stops Hiking, But Mortgage Rates Still Don’t Fall?
That scenario is entirely possible.
The RBA could hold the cash rate steady while global funding costs remain elevated.
Fixed rates could remain high.
Variable-rate competition could soften.
And banks could wait before passing lower funding costs through to borrowers.
None of this means mortgage rates must rise indefinitely.
Bond markets can reverse.
Inflation can fall.
Oil prices can decline.
Competition can intensify.
The RBA may eventually reduce rates.
But borrowers should avoid assuming that one RBA decision determines everything.
Your mortgage exists inside a global financial market.
And right now, that global market is becoming more expensive.
Is Your Home Loan Still Competitive?
Loan & Own Mortgages helps Australian homeowners and buyers review their lending position and compare suitable options across its lender panel.
A review can consider your current mortgage rate, loan structure, equity, LVR, fixed or variable options and the pricing available from other lenders.
You cannot control global bond markets.
But you can understand whether your current mortgage is still competitive within the market available to you.
Key sources
Reuters reported on 29 September that global sovereign bond markets were heading for one of their worst months in years, with US two-year yields up almost 60 basis points during September and global 10-year yields reaching multi-year highs. Reuters
Reuters reported on 8 October that UK 10-year yields reached 5.527%, their highest level since 2007, while Brent crude rose to around US$105 a barrel amid renewed inflation and geopolitical concerns. Reuters
The RBA says bank funding costs and lending rates are closely connected, with deposits representing around two-thirds of major-bank funding and debt accounting for almost one-third. Reserve Bank of Australia
The RBA's August Statement on Monetary Policy said major-bank funding costs had risen during 2026 as higher cash rates flowed through into deposit and wholesale debt costs. Reserve Bank of Australia
The RBA cash-rate target currently stands at 4.60%, with the next decision scheduled for 3 November 2026. Reserve Bank of Australia
This article provides general information only and does not constitute personal financial, credit, investment, tax or legal advice. Mortgage rates, lender pricing, wholesale funding costs and lending eligibility can change and depend on individual circumstances.
