Four RBA Rate Hikes Now Add Around $4,320 a Year to a $600,000 Mortgage
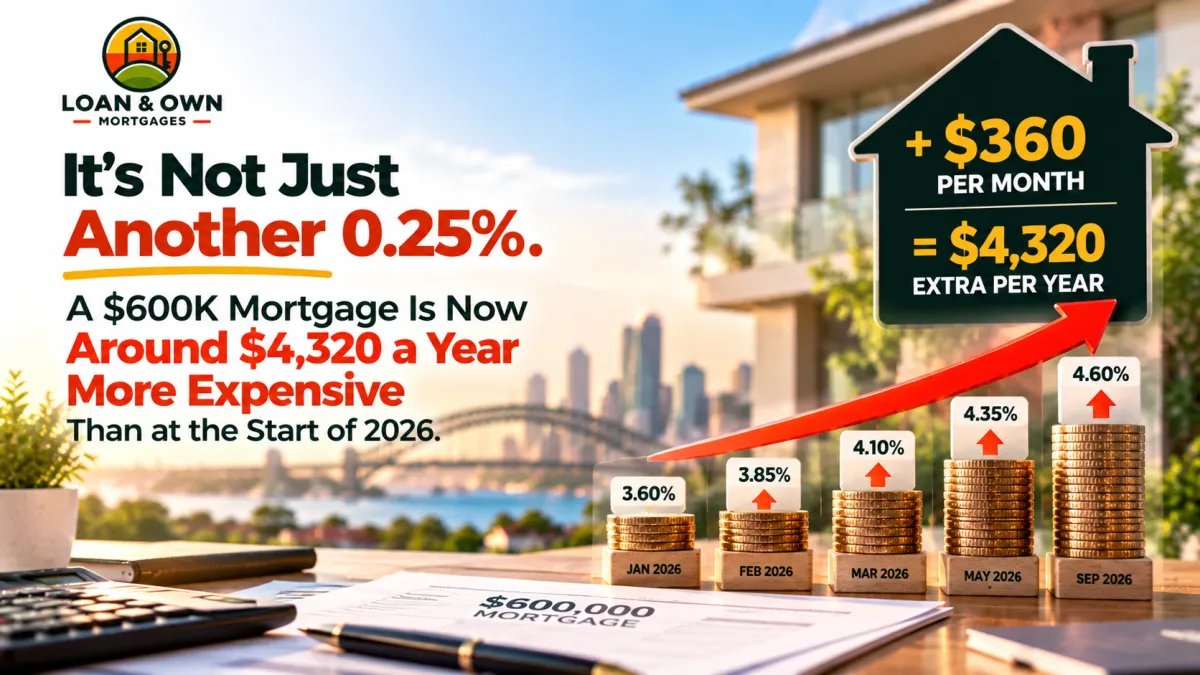
It’s Not Just Another 0.25%. A $600K Mortgage Is Now Around $4,320 a Year More Expensive Than at the Start of 2026.
A quarter of a percentage point sounds small.
For many Australian mortgage holders, however, yesterday's interest-rate increase was not really about another 0.25%.
It was about the cumulative effect of four increases during 2026.
The Reserve Bank of Australia increased the cash-rate target by another 25 basis points on 29 September, taking it from 4.35% to 4.60%. The increase becomes effective from 30 September and represents the fourth 25-basis-point increase this year. The cash rate began 2026 at 3.60%. Reserve Bank of Australia
That means the cash rate has now risen by a full percentage point during 2026.
For a borrower with a $600,000 variable mortgage and 25 years remaining, ABC estimates the latest increase alone adds approximately $91 per month if the lender passes it through in full.
Across the four increases this year, the cumulative increase is around $360 per month, or approximately $4,320 every year. ABC News
Canstar's modelling puts the cumulative monthly increase slightly higher at $364, which equates to $4,368 per year. The small difference reflects modelling and rounding assumptions. Canstar
Either way, the broader message for borrowers is the same:
Four relatively small interest-rate increases have become a meaningful change to the household budget.
What Four 2026 Rate Hikes Mean in Dollars
Canstar modelled the impact using an owner-occupier principal-and-interest mortgage with 25 years remaining at the beginning of the 2026 hiking cycle.
Its estimates show:
Loan balance at start of hikes | Latest 0.25% increase | Cumulative monthly increase after 4 hikes | Approx. annual increase |
|---|---|---|---|
$600,000 | $91 | $364 | $4,368 |
$800,000 | $122 | $485 | $5,820 |
$1,000,000 | $152 | $606 | $7,272 |
Source: Canstar modelling, assuming each cash-rate increase is passed through in full. Canstar
ABC uses a rounded cumulative figure of approximately $360 a month for the $600,000 example, equivalent to around $4,320 annually. ABC News
These calculations illustrate why focusing only on yesterday's $91 increase can understate the impact.
For someone with a $600,000 mortgage, the more useful comparison is not:
"What did yesterday's increase cost me?"
It is:
"How much more am I paying now compared with the beginning of this year?"
Four 25-Basis-Point Moves Have Added Up to a Full Percentage Point
Australia entered 2026 with the cash rate at 3.60%.
The RBA then increased it to:
3.85% in February,
4.10% in March,
4.35% in May,
and 4.60% following the September meeting. Reserve Bank of Australia
Each individual move was only 0.25 percentage points.
Together, they represent 1.00 percentage point of monetary tightening.
That cumulative perspective matters enormously for mortgage holders.
Someone who could comfortably absorb the first increase may feel differently after the fourth.
Why Does a 0.25% Increase Add About $91 to a $600,000 Loan?
Mortgage repayments depend on more than the interest rate.
They also depend on:
the outstanding loan balance,
the remaining term,
whether repayments are principal and interest or interest only,
and the lender's actual mortgage rate.
For Canstar's example, the borrower has a $600,000 owner-occupier principal-and-interest mortgage with 25 years remaining.
When the interest rate increases, more money is required each month to ensure the mortgage can still be fully repaid within that remaining term.
For the latest 25-basis-point increase, that means approximately another $91 per month. Canstar
The larger the mortgage, the bigger the dollar impact.
That is why a $1 million borrower faces an estimated $152 increase from this latest move and around $606 more each month across the four 2026 increases.
$360 a Month Can Look Very Different Inside a Household Budget
An extra $360 every month represents approximately:
$83 a week,
$4,320 a year,
or more than $21,000 across five years if that higher repayment level persisted.
The five-year comparison is illustrative because mortgage rates will almost certainly change during that period.
But it demonstrates the scale of the cash-flow effect.
For a household already paying more for:
groceries,
fuel,
insurance,
electricity,
childcare,
council rates,
and other everyday expenses,
an additional $360 does not exist in isolation.
It has to come from somewhere.
That could mean:
less discretionary spending,
lower savings,
smaller offset contributions,
postponed purchases,
more working hours,
or reduced financial buffers.
This cash-flow channel is one of the primary ways higher interest rates are intended to slow economic demand. ABC cited CBA economist Belinda Allen explaining that higher borrowing costs can lead mortgage holders to reduce spending or use savings, helping monetary policy cool demand. ABC News
The RBA Is Intentionally Trying to Slow Spending
The higher repayments are not an accidental side effect of monetary policy.
They are part of how it works.
Yesterday's RBA statement said aggregate demand needs to remain subdued for a period so that capacity pressures ease and inflation returns sustainably to target. The Board said the previous three increases had already tightened financial conditions, but judged that additional tightening was necessary because inflation remained too high. Reserve Bank of Australia
In simple terms:
higher rates make debt more expensive,
mortgage repayments rise,
households have less money available elsewhere,
spending slows,
businesses face weaker demand,
and inflationary pressure should eventually ease.
But that process can be particularly uncomfortable for households carrying large variable mortgages.
Today's Inflation Data Shows Why the RBA Remains Concerned
There is an important update since yesterday's decision.
New inflation data released today shows Australia's annual CPI inflation rose to 4.0% in August, up from 3.5% in July.
Housing was the biggest contributor, with annual housing inflation of 5.7%.
Automotive fuel prices jumped 14.8% during August, driven by higher world oil prices and the remainder of federal fuel-excise relief unwinding.
Trimmed mean inflation remained at 3.6% for the third consecutive month. Forex Factory
That keeps underlying inflation above the RBA's 2% to 3% target range.
It also helps explain why mortgage holders should not automatically assume yesterday's increase will be reversed quickly.
Will Every Bank Pass the 0.25% Increase Through?
Not necessarily.
The RBA sets the cash rate.
Banks set their own mortgage rates.
Historically, major lenders frequently pass cash-rate increases through to variable mortgages, but they decide the timing and amount themselves.
Macquarie was quick to respond yesterday, announcing that its variable home-loan reference rates would rise by 0.25 percentage points from 15 October. ABC News
As of the latest published updates, ANZ and Westpac said they were reviewing their mortgage pricing following the RBA decision. ANZ
That distinction is important.
The repayment figures in this article assume lenders pass the RBA increase through in full.
Your actual change depends on your lender, mortgage product and interest rate.
Your Starting Mortgage Rate Matters as Much as the RBA Increase
Consider two borrowers who both owe $600,000.
Borrower A is already on a highly competitive mortgage rate.
Borrower B is paying considerably more because they have not reviewed their loan for several years.
Both might receive the same 0.25 percentage-point increase.
But Borrower B could still be paying substantially more overall.
This is particularly relevant because Australian lenders have recently been competing aggressively for mortgage customers.
Some lenders have reduced selected new-customer variable rates even while the RBA has been increasing the cash rate.
That means higher official interest rates do not automatically eliminate opportunities to negotiate or refinance.
A Rate Review Could Potentially Offset Part of the Increase
Imagine your lender increases your mortgage rate by 0.25%.
But after reviewing your loan, you negotiate a 0.20 percentage-point reduction from its existing customer pricing.
Your net rate increase would then be much smaller.
That outcome is not guaranteed.
But it illustrates why borrowers should look at their total mortgage rate rather than concentrating entirely on RBA decisions.
Before refinancing, an existing borrower could ask their lender:
"What is the best rate you can currently offer me?"
The lender may offer a retention discount.
If not, the borrower can then compare alternatives.
You Do Not Necessarily Need to Change Banks
Refinancing is not always required to improve a mortgage.
An existing lender may agree to reprice the loan.
That could potentially avoid:
new application paperwork,
discharge fees,
property valuation issues,
switching costs,
and a new lender assessment.
But borrowers should not assume their bank will proactively provide the strongest rate available.
Checking can matter.
Compare the Loan, Not Just the Headline Interest Rate
A lower advertised rate does not necessarily mean a cheaper mortgage overall.
Consider:
comparison rate,
annual fees,
offset-account fees,
package costs,
application fees,
discharge costs,
cashback conditions,
loan flexibility,
and the remaining mortgage term.
A borrower who refinances into a cheaper interest rate but resets a 20-year remaining loan into a new 30-year mortgage may reduce monthly repayments while potentially paying more interest over the long term.
The objective should be a better overall lending outcome, not simply the smallest advertised percentage.
Offset Accounts Become Even More Valuable When Rates Rise
For borrowers with an offset account, higher mortgage rates can make every dollar sitting in the offset more valuable.
Suppose you owe $600,000 but hold $80,000 in a 100% offset account.
Interest may effectively be calculated against approximately $520,000 rather than the entire $600,000 balance, subject to your loan's terms.
As rates rise, the interest avoided through the offset also increases.
That does not mean an offset account is automatically the best structure for everyone.
Some offset products have higher fees or rates.
But borrowers with existing offsets should understand how effectively they are using them.
Redraw and Offset Are Not the Same Thing
Borrowers sometimes treat these features as interchangeable.
They are not.
Money in an offset account remains in a separate transaction account linked to the mortgage.
Extra repayments placed into the loan may instead become available through redraw, subject to lender conditions.
There can also be tax implications for investment properties when money is withdrawn and reused.
Borrowers considering major structural changes should therefore understand how their loan features actually operate before moving funds.
Fixed-Rate Borrowers Will Not Feel Yesterday's Increase Immediately
If your mortgage is currently fixed, your contracted interest rate generally does not change simply because the RBA raises the cash rate.
That creates short-term protection.
But the key date becomes the end of the fixed period.
A borrower who fixed before the 2026 hiking cycle could eventually roll onto a substantially higher variable rate.
That can create a much larger repayment change all at once.
Fixed-rate borrowers approaching expiry should therefore review:
the expiry date,
the lender's revert rate,
available fixed options,
variable alternatives,
and refinancing possibilities
before the fixed period ends.
Recent Buyers May Feel the Four Increases More Sharply
Someone who bought a home years ago may have:
a smaller outstanding mortgage,
substantial equity,
and larger savings buffers.
A recent buyer may instead have:
a larger mortgage,
a smaller deposit,
less accumulated equity,
and fewer cash reserves.
The same 0.25 percentage-point rate increase can therefore have very different effects.
That is why household-level circumstances matter more than national averages.
Higher Rates Are Also Reducing Borrowing Capacity
The effect of the 2026 rate cycle is not confined to existing borrowers.
Prospective home buyers are also being affected.
Canstar estimates an individual earning the average full-time wage has lost more than $47,000 in maximum borrowing capacity across this year's increases.
For a couple both earning that average wage, the estimated reduction approaches $95,000. ABC highlighted those figures in its post-RBA analysis. ABC News
So higher interest rates are affecting both sides of Australia's housing market.
Existing owners:
higher repayments.
Prospective buyers:
lower borrowing capacity.
Higher Repayments Can Feed Back Into the Housing Market
Yesterday's RBA statement acknowledged that housing prices have fallen in most capital cities and new housing loans have declined noticeably. Reserve Bank of Australia
Higher mortgage repayments can reinforce that trend.
As buyers' borrowing capacity falls:
fewer households can bid at previous price levels,
investors may become more cautious,
property turnover can weaken,
and sellers may need to adjust expectations.
That creates an important feedback loop.
Higher rates weaken housing.
A weaker housing market can reduce household wealth and spending.
That can eventually help slow inflation.
The RBA therefore needs to judge how much tightening is enough.
Could There Be Another Rate Increase?
The RBA has not ruled it out.
Its 29 September statement explicitly said the Board would continue doing what it considers necessary to bring inflation sustainably back to target, including increasing the cash rate further if required. Reserve Bank of Australia
Economists do not agree on what comes next.
ABC reported that a majority of analysts surveyed by Bloomberg expected yesterday's increase to be the final hike of 2026, while ANZ, HSBC and UBS were among those still seeing the possibility of another increase. ABC News
Today's higher headline CPI reading adds another important piece of evidence for the RBA to consider.
No borrower can know the next decision with certainty.
That makes scenario planning more useful than prediction.
What Would a Fifth Hike Mean?
Canstar has previously modelled another 25-basis-point increase after September.
For a $600,000 mortgage with 25 years remaining, an additional increase was estimated to add roughly another $92 per month.
That would take the cumulative increase across five 2026 hikes to approximately $456 per month.
For a $1 million mortgage, the cumulative increase could reach around $759 per month under the same assumptions. Canstar
Again, this is a scenario rather than a forecast.
But borrowers can use it to stress-test their household budget.
Do Not Wait for Mortgage Stress to Review the Loan
A mortgage review does not need to begin after repayments become difficult.
Earlier can be better.
Check:
your actual interest rate,
your current mortgage balance,
your approximate property value,
your LVR,
your available offset or redraw balance,
your remaining loan term,
and comparable lender pricing.
If your mortgage rate is competitive and the structure suits you, staying with the existing lender may be completely appropriate.
If it is not, understanding the alternatives gives you choices.
The Bigger Lesson: Stop Looking at Rate Hikes One at a Time
Yesterday's increase was 0.25%.
That is technically correct.
But it does not describe the lived experience of many Australian mortgage holders.
A $600,000 borrower has not simply absorbed one $91 monthly increase.
Across the four RBA increases in 2026, the cumulative repayment impact is now approximately $360 to $364 every month under the commonly used 25-year variable-loan example. ABC News
That is around:
$4,320 to $4,368 annually.
For a $1 million mortgage:
approximately $606 extra each month,
or about $7,272 annually.
At those levels, mortgage pricing becomes worth reviewing.
It’s Not Just Another 0.25%. It’s Four Increases in One Year.
The RBA has now taken the cash rate from 3.60% at the beginning of 2026 to 4.60%. Reserve Bank of Australia
For mortgage borrowers, focusing only on yesterday's increase misses the bigger story.
The cumulative effect is what changes household budgets.
It affects spending.
Savings.
Borrowing capacity.
Property decisions.
And financial flexibility.
A quarter-point increase can sound small.
Four of them do not.
Has Your Mortgage Kept Up With the Market?
At Loan & Own Mortgages, we help Australian homeowners review their existing mortgage and understand whether their current rate and loan structure remain competitive.
That can include reviewing your:
interest rate,
repayments,
equity and LVR,
offset structure,
refinancing options,
lender pricing,
and potential switching costs.
You cannot control the RBA cash rate.
But you can understand whether you are paying more than you need to within the market available to you.
Speak with Loan & Own Mortgages to review your home loan following the latest RBA increase.
Data sources
Reserve Bank of Australia, 29 September 2026: The Monetary Policy Board unanimously increased the cash-rate target by 25 basis points to 4.60%. The RBA said inflation remained too high and stated that further tightening remains possible if necessary. Reserve Bank of Australia
Reserve Bank of Australia cash-rate history: The rate increased from 3.60% at the beginning of 2026 to 3.85% in February, 4.10% in March, 4.35% in May and 4.60% effective 30 September. Reserve Bank of Australia
ABC News, 29 September 2026: A 25-basis-point increase adds approximately $91 per month to a $600,000 variable mortgage with 25 years remaining. ABC estimates the four 2026 hikes have increased repayments by about $360 monthly, equivalent to approximately $4,320 per year. ABC News
Canstar, September 2026: Canstar's modelling estimates four increases add $364 a month to a $600,000 mortgage, $485 to an $800,000 mortgage and $606 to a $1 million mortgage, assuming the increases are passed through in full. Canstar
Australian inflation update, 30 September 2026: Annual CPI inflation rose from 3.5% in July to 4.0% in August. Housing inflation was 5.7%, while annual trimmed mean inflation remained at 3.6%. Forex Factory
ABC News, 30 September 2026: The latest increase takes Australia's cash rate to its highest level in almost 15 years, adding further pressure to mortgage borrowers following four increases in 2026. ABC News
This article provides general information only and does not constitute personal financial, credit, investment, tax or legal advice. Actual repayment changes depend on your mortgage balance, interest rate, remaining term, repayment structure, lender decisions and individual circumstances.
