Your Bank Just Cut Mortgage Rates. Did They Cut Yours?
Your Bank Just Cut Mortgage Rates. Did They Cut Yours?
Australian mortgage competition is heating up again.
But there is an important catch.
The best new home-loan offers may not automatically be flowing through to the people who have already been loyal customers for years.
ABC reported on 14 September that banks are increasingly cutting selected variable mortgage rates as they compete for fewer borrowers.
Commonwealth Bank cut rates across a range of mortgage products in late June.
ANZ and Westpac quickly followed.
Macquarie Bank also reduced rates in July.
Mortgage broker Julian Choo told ABC that dozens of lenders had lowered variable rates during the previous month.
That sounds like good news for Australian homeowners.
But according to Choo, much of that aggressive pricing is aimed at attracting new customers rather than automatically rewarding existing ones.
For borrowers, that creates a very practical question:
Is the rate you are paying today still competitive?
Mortgage Competition Is Increasing Even While Rates Remain High
Australia is in an unusual lending environment.
The RBA has increased interest rates during 2026.
At the same time, lenders are competing aggressively for market share.
The Reserve Bank itself noted in its August Statement on Monetary Policy that some lenders had reduced advertised variable mortgage rates since June, with selected products cut by as much as 20 to 30 basis points.
The RBA said those reductions were consistent with strong competition among lenders as housing-credit growth slows.
Canstar identified the same trend.
By August, 49 lenders were offering at least one variable mortgage rate below 6%, compared with 38 lenders at the beginning of June.
Canstar also found that 31 lenders had reduced new-customer variable rates since the start of June.
Earlier, Canstar reported that 23 lenders had cut at least one variable rate between May and mid-July despite RBA rate increases.
Those cuts applied primarily to new borrowers.
That is the key distinction.
Mortgage rates can move even when the RBA does nothing.
And the rate available to a new borrower may not be the same rate an existing customer is currently paying.
Why Do Banks Offer Better Deals to New Customers?
Mortgage lending is an extremely competitive business.
A home loan can remain with a bank for decades.
That makes acquiring a new mortgage customer potentially valuable.
Banks may therefore offer:
lower introductory rates,
larger discounts from their standard variable rate,
cashback,
fee waivers,
or other incentives
to convince borrowers to move.
Existing customers, meanwhile, may simply continue making repayments without checking whether their rate remains competitive.
That behaviour can reduce the pressure on the lender to offer them its newest pricing.
Julian Choo summarised the problem bluntly in the ABC investigation: lenders generally do not proactively promote their strongest deals to existing borrowers.
Does This Mean Every Existing Customer Is Paying More?
No.
This point is important.
It would be misleading to suggest every long-term borrower is paying substantially more than every new customer.
RBA data shows the average gap between new and existing variable mortgage rates has narrowed considerably over recent years.
The RBA reported that the spread between the average outstanding variable mortgage rate and the average new variable mortgage rate had fallen from around 35 basis points in 2019 to approximately 3 basis points by December 2025.
The RBA's July 2026 lending-rate data also showed:
Loan type | Outstanding loans | New loans |
|---|---|---|
Owner-occupier P&I | 6.19% | 6.16% |
Owner-occupier interest-only | 6.85% | 6.98% |
Investor P&I | 6.38% | 6.32% |
Investor interest-only | 6.57% | 6.50% |
These are market averages, not individual offers.
So at an aggregate level, the new-versus-existing gap is relatively small.
But averages can hide large differences between individual borrowers.
Some existing customers may already have competitive discounts.
Others may be paying materially more than rates currently available elsewhere.
That is why the useful question is not:
"Are existing customers always worse off?"
It is:
"How does my specific rate compare?"
The Difference Between Advertised Rates and What You Actually Pay
Mortgage pricing can be confusing because several different rates may appear around the same product.
There may be:
a headline interest rate,
a comparison rate,
a standard variable rate,
an individual customer discount,
a refinance-only rate,
or a new-customer promotional rate.
Borrowers should therefore check the actual rate currently being charged on their loan rather than relying on what they remember signing up for.
The rate shown on your most recent mortgage statement or online banking account is the number that matters for comparison.
The Mortgage "Loyalty Tax"
The phrase "loyalty tax" is often used to describe situations where long-standing customers pay more than new customers for effectively similar products.
This issue has existed in mortgage lending for years.
The RBA notes that new customers historically tended to receive lower mortgage pricing because they were more price sensitive and lenders competed aggressively to win their business.
However, borrower behaviour has changed considerably.
The refinancing surge during 2023 and 2024 forced lenders to work harder to retain existing customers.
Some banks simplified pricing-review requests.
Others offered better rates to borrowers rolling off fixed loans.
Mortgage brokers also helped existing customers negotiate improved pricing without necessarily changing lenders.
That competition dramatically reduced the average loyalty gap.
But it did not eliminate the need for individual borrowers to check their rate.
You Do Not Necessarily Need to Refinance to Get a Better Deal
This may be the most useful takeaway for existing homeowners.
Before switching lenders, consider asking your existing lender for a pricing review.
The conversation can be relatively simple.
You can ask:
"What is the best rate you can currently offer me on my existing loan?"
A lender may agree to reduce the interest rate to retain the customer.
There is no guarantee they will.
But obtaining an internal rate reduction can have several advantages.
You may avoid:
a new mortgage application,
property valuation complications,
discharge fees,
new lender fees,
potential LMI,
and the administrative work involved in moving banks.
For borrowers with limited equity, this can be particularly valuable.
Why This Matters Even More for Recent Buyers
As we discussed in the previous LNO Mortgages article, some recent buyers are finding it harder to refinance because falling property values have reduced their equity.
A borrower might discover a better rate elsewhere but struggle to switch because their loan-to-value ratio has increased.
In that situation, negotiating with the existing lender can become even more important.
You may not need to pass another lender's full refinance assessment just to ask your current bank for better pricing.
That does not mean the current lender will always provide the best outcome.
But it gives borrowers another option when refinancing is difficult.
What Difference Could 0.50% Actually Make?
A rate difference that looks small can become significant when applied to a large mortgage.
Consider an illustrative owner-occupier mortgage of:
Loan balance: $600,000
Remaining term: 25 years
Current interest rate: 6.30%
Alternative rate: 5.80%
At 6.30%, the approximate monthly principal-and-interest repayment would be:
$3,977 per month
At 5.80%, it would be approximately:
$3,793 per month
Difference:
approximately $184 per month
or around:
$2,206 per year
This is only an illustration.
Actual savings depend on the loan balance, remaining term, fees, repayment structure and whether the lower rate remains available.
But it demonstrates why relatively small pricing differences matter on large mortgages.
Do Not Compare the Interest Rate Alone
A lower advertised rate is attractive.
But refinancing decisions should consider the entire loan.
Important factors include:
interest rate,
comparison rate,
annual package fees,
offset account availability,
redraw facilities,
cashback conditions,
application fees,
discharge costs,
loan term,
fixed versus variable structure,
and any LMI implications.
Canstar notes that refinance offers may include cashback of up to several thousand dollars, but warns that borrowers should not choose a home loan purely because of a promotional incentive.
The underlying rate, fees and features still matter.
Cashback Can Look Better Than It Really Is
Imagine one lender offers:
$3,000 cashback
but charges a slightly higher mortgage rate.
Another lender offers no cashback but has a materially cheaper rate.
Over several years, the second option could potentially save significantly more.
Some cashback offers also contain:
minimum loan amounts,
maximum LVR requirements,
time limits,
clawback provisions,
or restrictions on which borrowers qualify.
A mortgage should normally be evaluated over the expected period you intend to hold it, not simply based on the first-year incentive.
New-Customer Deals Can Have Eligibility Rules
Not every advertised rate is available to every borrower.
For example, some products require:
an LVR of 80% or lower,
a minimum loan balance,
owner-occupier status,
principal-and-interest repayments,
direct online application,
or refinancing from another financial institution.
CommBank's current Digi Home Loan offer, for example, requires eligible borrowers to refinance from another financial institution and excludes existing CommBank mortgage customers from using that specific refinance offer.
ME Bank similarly states that certain mortgage discounts apply to new home-loan applications and exclude existing applications, internal refinancing, top-ups and variations.
This is why comparing advertisements alone can be misleading.
The important question is whether you actually qualify.
Why Banks Are Fighting Harder for Mortgage Customers
The housing market has slowed.
New lending activity has weakened.
Property prices have been falling.
That means lenders are competing over a smaller pool of borrowers.
ABC described the current environment as banks trying to win a bigger share of a smaller mortgage market.
At the same time, Macquarie Bank has become a more significant competitor to the traditional Big Four.
That pressure can benefit borrowers.
When lenders compete, they may:
cut rates,
increase discounts,
improve features,
offer refinance incentives,
or negotiate more aggressively to retain customers.
The customer who compares their options can therefore potentially benefit from competition.
The customer who never asks may not.
The RBA Is Not the Only Thing That Changes Mortgage Rates
Australian borrowers naturally follow every RBA announcement.
But today's mortgage market demonstrates why that is only part of the story.
The RBA sets the cash rate.
Banks determine their individual lending rates.
Those rates are influenced by:
funding costs,
competition,
market share targets,
credit risk,
loan type,
borrower profile,
loan-to-value ratio,
and wholesale financial markets.
The RBA itself says strong lender competition has kept mortgage lending spreads relatively low by historical standards.
So even while the cash rate is elevated, some lenders can selectively cut particular products.
You Could Be Waiting for an RBA Cut That Never Reaches You Automatically
This is an important behavioural trap.
Borrowers sometimes think:
"I'll review my mortgage after the RBA cuts rates."
But lenders are already changing pricing outside the RBA cycle.
Some are reducing selected mortgage rates today.
That means borrowers who wait exclusively for the central bank may miss opportunities available in the current competitive market.
The relevant question is not only:
"What will the RBA do?"
It is also:
"What are lenders doing right now?"
Check Your Current Rate Against the Market
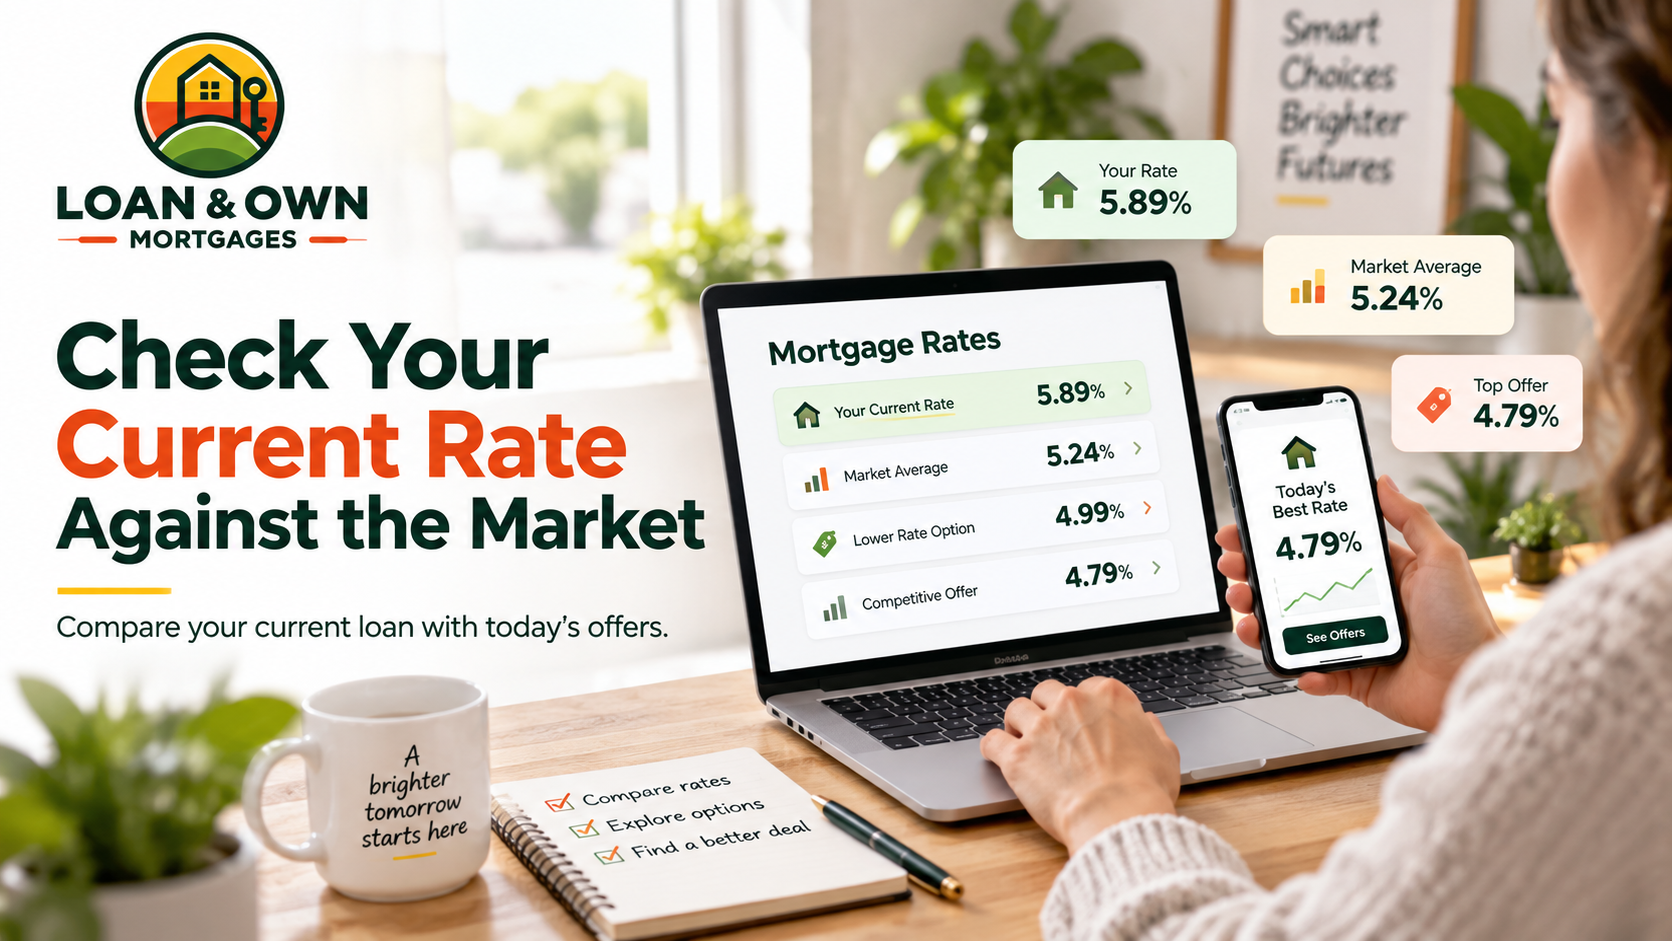
A simple mortgage health check starts with three numbers.
Your current interest rate.
Your outstanding balance.
Your estimated property value.
From there, you can estimate your LVR and compare your existing mortgage against current products.
You should also know:
your remaining loan term,
whether your mortgage has an offset,
whether annual fees apply,
whether the loan is fixed or variable,
and whether switching would create additional costs.
Those details help determine whether the current loan remains competitive.
First Ask Your Current Lender
The easiest potential saving may be available without refinancing.
Call your current lender and ask for a rate review.
It may help to know what competing lenders are offering before making the call.
You can explain that you are reviewing your mortgage and ask whether they can offer a better interest rate.
If they improve your pricing sufficiently, staying may make sense.
If not, you have more information for comparing alternatives.
Then Compare Other Lenders
If your current lender does not provide a competitive offer, the next step is to understand the broader market.
Comparison should consider more than the lowest rate displayed on a website.
A lender may look attractive until you account for:
LVR restrictions,
serviceability requirements,
fees,
loan features,
refinance costs,
valuation outcomes,
and lender policy.
A mortgage broker can compare multiple lenders against your actual circumstances rather than simply comparing advertisements.
Open Banking Can Make Comparison Easier
Competition is also being supported by Australia's Consumer Data Right.
From July 2026, non-bank lenders began sharing product information including rates, fees, charges and eligibility criteria through the Consumer Data Right framework.
The ACCC says the expansion should help consumers access broader loan comparisons and better-value options.
This increases transparency.
But borrowers still need to interpret whether a product actually suits their circumstances.
Should You Switch for a Small Rate Difference?
Not necessarily.
Suppose another lender offers a rate 0.10% below your current loan.
If switching costs are high, the financial benefit may take years to recover.
A borrower should calculate the break-even period.
For example:
total switching costs ÷ monthly repayment saving = approximate number of months required to recover the switching cost.
If you plan to sell the property before reaching that point, refinancing may not make sense.
If the rate difference is much larger and the loan balance is substantial, the economics can look very different.
Be Careful About Extending the Loan Term
Another common refinance trap is restarting a mortgage over 30 years.
A borrower with 20 years remaining may refinance into a new 30-year loan.
That can substantially reduce the monthly repayment.
But part of the reduction comes from spreading the debt over an additional decade.
The borrower may ultimately pay more total interest even at a lower interest rate.
Always compare:
current remaining term,
proposed new term,
monthly repayment,
and estimated total interest.
Your Existing Loan Features May Be Valuable
Interest rate is important.
But borrowers should also consider the value of loan features.
An offset account may save considerable interest for someone who keeps a significant cash balance.
A redraw facility can provide flexibility.
Extra repayment options may matter.
Fixed-rate flexibility may matter.
Some borrowers may prefer a slightly higher rate if the mortgage structure better suits the way they manage money.
The goal is not simply to find the lowest advertised percentage.
It is to find the loan that creates the strongest overall outcome.
Mortgage Brokers Can Also Negotiate With Your Current Lender
A broker's role is not necessarily limited to moving borrowers to a new bank.
Depending on the lender and circumstances, brokers may also be able to request pricing reviews for existing clients.
The RBA has specifically noted that some borrowers have achieved better mortgage rates through brokers negotiating with their existing lender.
That can sometimes produce savings without the cost and complexity of a refinance.
The Bigger Lesson: Loyalty Should Not Replace Comparison
There is nothing inherently wrong with staying with the same bank for many years.
A long-term customer may already have an excellent interest rate, suitable features and good service.
The problem occurs when loyalty becomes inactivity.
A borrower can remain with the same lender while still reviewing their mortgage regularly.
The purpose of a home-loan review is not automatically to refinance.
It is simply to answer:
Is this still the right loan at a competitive price?
Your Bank Just Cut Mortgage Rates. Did They Cut Yours?
Australia's mortgage market is becoming increasingly competitive.
Dozens of lenders have reduced selected variable rates.
Some major banks have cut mortgage products.
More lenders are offering sub-6% options.
Yet many of the strongest advertised discounts are specifically designed to attract new borrowers.
Existing customers should not assume the latest rate reduction has automatically appeared on their mortgage.
Check.
Ask.
Compare.
A 10-minute mortgage review could reveal that your current rate is already competitive.
Or it might show that you are paying considerably more than necessary.
Either answer is useful.
When Did You Last Review Your Home Loan?
At Loan & Own Mortgages, we help Australian homeowners compare their current mortgage with available lender options.
That can include reviewing:
your existing interest rate,
loan features,
potential lender discounts,
refinancing costs,
property equity,
serviceability,
and whether switching would actually save money.
You may not need to change banks.
Sometimes the first opportunity is simply negotiating a better deal where you already are.
But you will not know until you compare.
Speak with Loan & Own Mortgages to find out whether your current home-loan rate is still competitive.
Data sources
ABC News, 14 September 2026: Major lenders are cutting selected mortgage rates as competition for borrowers increases. Mortgage broker Julian Choo said new customers frequently receive stronger pricing while existing borrowers may not automatically receive the same discounts.
Reserve Bank of Australia, August 2026 Statement on Monetary Policy: Some lenders reduced advertised variable mortgage rates by 20 to 30 basis points on selected products since June, reflecting strong competition for housing borrowers.
Reserve Bank of Australia lending-rate data: In July 2026, average owner-occupier principal-and-interest mortgage rates were 6.19% on outstanding loans and 6.16% on new lending.
RBA February 2026 Bulletin: The average new-versus-existing variable mortgage rate gap fell from roughly 35 basis points in 2019 to around 3 basis points by December 2025 as refinancing and customer negotiation increased.
Canstar, August 2026: 49 lenders were offering at least one variable mortgage rate below 6%, while 31 lenders had cut new-customer variable rates since the beginning of June.
ACCC, July 2026: The Consumer Data Right expanded to non-bank lenders, requiring them to share product information including rates, fees, charges and eligibility criteria to improve consumer comparison.
This article contains general information only and does not constitute personal financial, credit, investment, tax or legal advice. Mortgage rates, discounts, lender policies, fees, refinancing eligibility and savings depend on individual circumstances and can change without notice.
