The Big Four Have Made Their Move: Your Variable Mortgage Rate Rises From 9 October
The Big Four Have Made Their Move: Your Variable Mortgage Rate Rises From 9 October
The Reserve Bank's latest rate increase is no longer simply an announcement borrowers can watch from the sidelines.
Australia's four major banks have now confirmed exactly how they will respond.
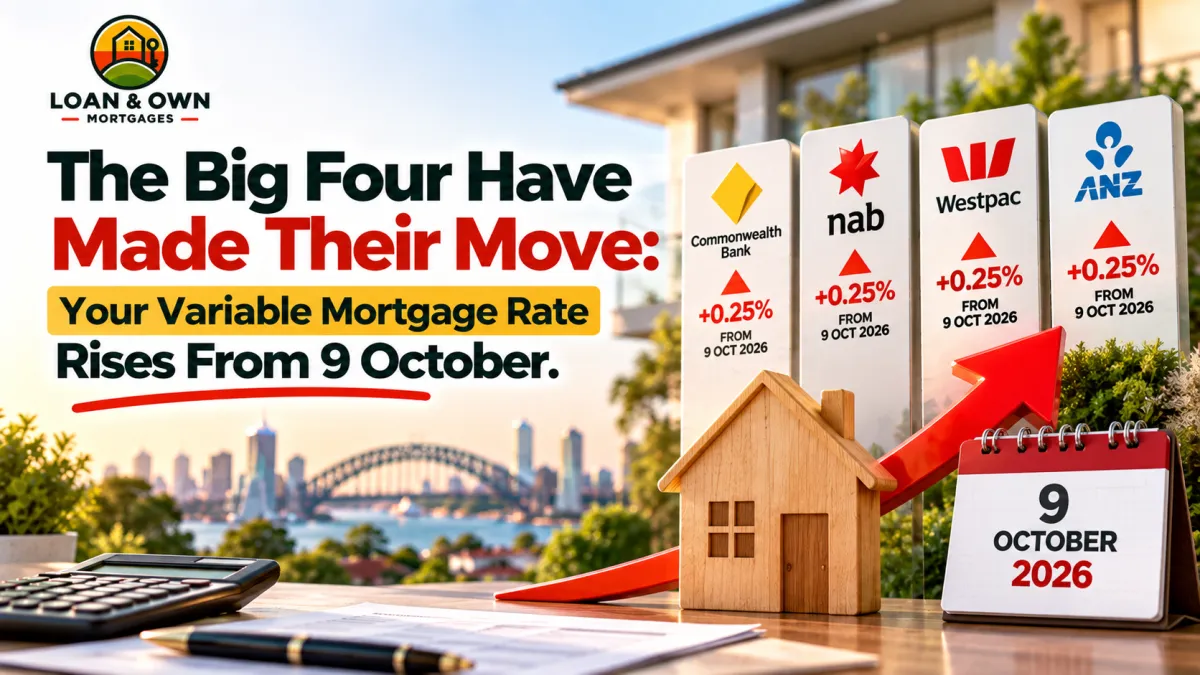
Commonwealth Bank, NAB, Westpac and ANZ will each increase variable home-loan rates by the full 0.25 percentage points from 9 October 2026. ABC News
Macquarie has also confirmed a 0.25 percentage-point increase to its variable home-loan reference rates, although its change takes effect slightly later, on 15 October. Macquarie Bank
The Reserve Bank increased Australia's cash-rate target from 4.35% to 4.60% on 29 September, marking another step higher in what has become a significant tightening cycle for mortgage borrowers. Reserve Bank of Australia
For variable-rate borrowers, the important question has therefore changed.
It is no longer:
"Will my bank pass the rate rise on?"
For customers of the Big Four, the answer is now clear.
The more useful questions are:
When does my rate change?
How much will my repayment increase?
And is my current mortgage still competitive once the new pricing takes effect?
The Key Dates Mortgage Holders Need to Know
The lender announcements create a clear timeline.
Lender | Variable home-loan change | Effective date |
|---|---|---|
Commonwealth Bank | +0.25 percentage points | 9 October 2026 |
NAB | +0.25 percentage points | 9 October 2026 |
Westpac | +0.25 percentage points | 9 October 2026 |
ANZ | +0.25 percentage points | 9 October 2026 |
Macquarie | +0.25 percentage points | 15 October 2026 |
ABC confirmed all four major banks are passing the RBA increase through in full. ABC News
The individual banks have also published their own announcements.
CBA says all variable home-loan changes announced following the RBA decision will become effective on 9 October. CommBank
NAB says its 0.25 percentage-point increase will also take effect from 9 October. NAB
ANZ confirmed variable rates across its Australian home loans will increase 0.25 percentage points from 9 October. ANZ
Westpac likewise confirmed a full 0.25 percentage-point increase for new and existing variable home-loan customers from 9 October. Westpac
Macquarie's change takes effect on 15 October. Macquarie Bank
Why 9 October Matters More Than the RBA Announcement Date
The RBA made its decision on 29 September.
But that does not mean a Big Four mortgage rate changed immediately on 29 September.
For these banks, the relevant home-loan pricing date is 9 October.
That creates a short window in which borrowers can understand what their mortgage may look like after the change.
It is an opportunity to check:
your current variable rate,
your loan balance,
your existing monthly or fortnightly repayment,
your approximate equity,
whether your lender's pricing remains competitive,
and whether another lender offers a materially different overall loan structure.
The exact date a minimum repayment amount changes can depend on the lender's systems, repayment cycle and individual loan arrangements, so borrowers should check their bank's notification rather than assume the payment itself changes precisely on 9 October.
But the interest-rate change itself is now known.
CBA Is Passing the Increase Through in Full
Commonwealth Bank was explicit.
Following the RBA's 0.25 percentage-point increase, CBA will increase variable home-loan interest rates by the same amount.
The change becomes effective on 9 October. CommBank
CBA said borrowers may need to reassess budgets and repayment arrangements and encouraged customers concerned about their position to discuss available options.
This matters because CBA is Australia's largest home lender.
A full pass-through therefore affects a substantial number of Australian mortgage holders.
NAB Is Doing the Same
NAB also confirmed the entire RBA increase will be passed on to variable home-loan customers.
Its new rates take effect from 9 October. NAB
NAB's own mortgage guidance illustrates how quickly relatively small rate moves can affect household budgets.
For example, its published scenario modelling shows a 0.25 percentage-point increase can add around $81 per month to a $500,000, 30-year principal-and-interest loan at a starting rate of 6.00%, although the exact change depends on the customer's balance, rate and remaining term. NAB
The important point is not the exact $81 figure.
It is that every increase compounds on top of the previous ones.
ANZ Has Confirmed a Full 0.25% Increase
ANZ has also confirmed variable rates across its Australian home loans will increase by 0.25 percentage points from 9 October. ANZ
ANZ estimates that a 0.25 percentage-point increase would add approximately $79 per month to repayments on an illustrative $500,000 owner-occupier principal-and-interest mortgage. ANZ
Again, that is only an example.
A borrower owing $800,000 or $1 million will experience a much larger dollar change.
Someone with $250,000 remaining will experience less.
That is why borrowers need to calculate the impact based on their own loan rather than rely only on national averages.
Westpac Will Increase Rates for New and Existing Variable Customers
Westpac's announcement is similarly straightforward.
It will increase variable home-loan rates by 0.25 percentage points for both new and existing customers from 9 October. Westpac
Westpac acknowledged that the tightening cycle continues to place pressure on household budgets.
That is particularly important after multiple increases during 2026.
A borrower is not simply absorbing the latest quarter-point change.
They are carrying the cumulative effect of the entire tightening cycle.
Macquarie Borrowers Have a Different Date
Macquarie is also passing through the full 0.25 percentage-point increase to its variable home-loan reference rates.
But its effective date is 15 October rather than 9 October. Macquarie Bank
Macquarie says customers will be able to see their new rates through its digital banking channels from the effective date, with repayment changes communicated according to the customer's individual loan arrangements. Macquarie Bank
This difference highlights something borrowers often overlook.
The RBA makes one national decision.
But individual lenders determine:
whether they pass it through,
how much they pass through,
when it becomes effective,
and how customer repayments are adjusted.
The Cash Rate Is Now 4.60%
The RBA increased the cash-rate target to 4.60% because it believes inflation remains too high and several upside inflation risks are materialising.
The RBA specifically highlighted higher global energy prices, technology-related price pressures associated with strong AI investment demand and continuing domestic capacity constraints. Reserve Bank of Australia
The Board also noted that housing prices have fallen across most capital cities and new housing lending has declined noticeably.
That illustrates the difficult balance facing monetary policy.
Higher rates are already weakening housing and household demand.
But inflation remains sufficiently elevated that the RBA judged another increase necessary.
What Could the Latest Increase Mean for a $600,000 Mortgage?
Earlier modelling around the RBA move estimated the latest 0.25 percentage-point increase could add about $91 per month to a $600,000 variable mortgage with 25 years remaining, assuming the lender passes the increase through in full.
We now know the Big Four are doing exactly that.
So for a borrower matching those assumptions, the latest increase translates to approximately:
$91 more per month
or around:
$1,092 more per year.
But the cumulative effect is more significant.
Across the four 2026 increases, the same illustrative borrower is paying roughly $360 more each month than at the beginning of the year.
That is around $4,320 annually.
For a $1 million mortgage, the cumulative effect is around $606 per month under similar assumptions.
The RBA decision might be expressed as 25 basis points.
Household budgets experience it in dollars.
Your Actual Increase Could Be Different
Those examples are useful illustrations, but they should not be treated as personalised repayment quotes.
Your actual change depends on:
your outstanding mortgage balance,
your current interest rate,
remaining loan term,
principal-and-interest versus interest-only structure,
repayment frequency,
offset balance,
and your lender's repayment-calculation method.
Two customers at the same bank can therefore see different repayment increases even though both rates rise by exactly 0.25 percentage points.
Fixed-Rate Borrowers Are in a Different Position
If your mortgage is fully fixed, the 9 October variable-rate changes generally do not alter your contracted fixed rate during the fixed period.
But that does not mean the latest RBA move is irrelevant.
The important number becomes your fixed-rate expiry date.
When a fixed loan ends, the borrower may revert to a substantially higher variable rate unless another arrangement is made.
That can result in a much larger repayment adjustment than the 0.25 percentage-point increase variable customers experience immediately.
Fixed-rate borrowers approaching expiry should therefore know:
their expiry date,
their revert rate,
available variable pricing,
new fixed-rate alternatives,
and whether refinancing is practical.
Split Loans Will Feel Only Part of the Change
Some borrowers divide their mortgage between fixed and variable components.
For example:
$300,000 fixed
and
$300,000 variable.
In that situation, the variable portion is exposed to the latest lender increase while the fixed portion remains unchanged during its agreed period.
The household impact will therefore be smaller than it would be on a fully variable $600,000 loan.
Understanding your loan structure is essential before calculating the effect.
The Big Four Passing the Hike in Full Does Not Mean Every Mortgage Has the Same Rate
This is perhaps the most important distinction.
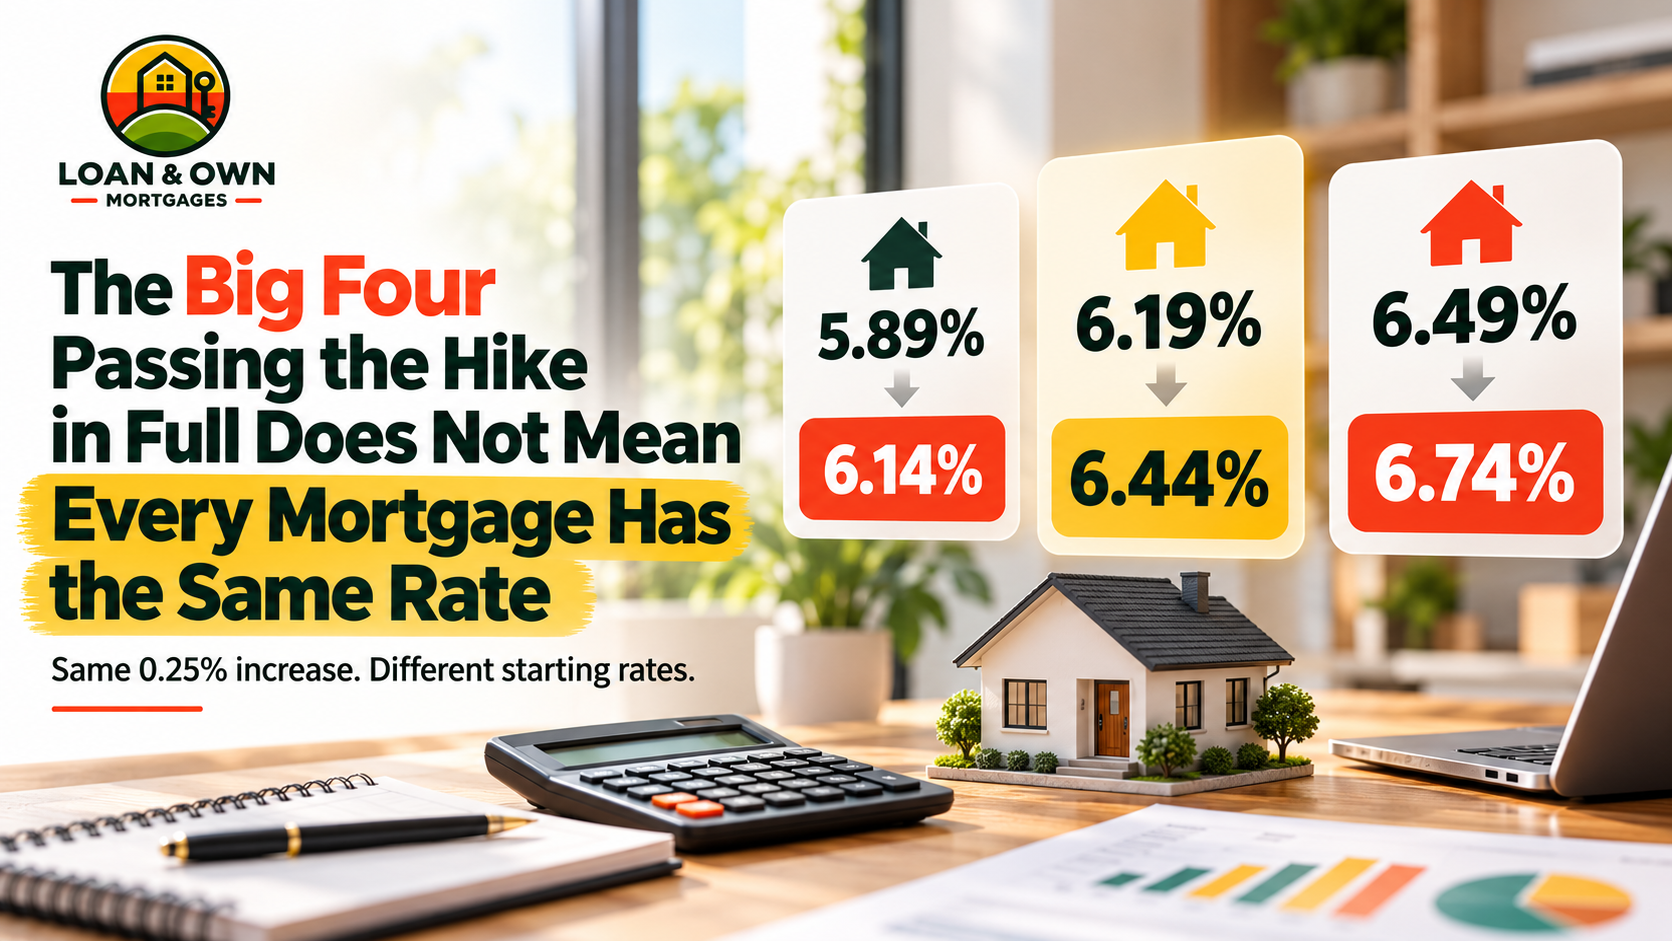
CBA, NAB, Westpac and ANZ are all increasing variable home-loan rates by the same 0.25 percentage points.
That does not mean their customers will all end up paying identical mortgage rates.
One borrower might move from:
5.89% to 6.14%.
Another might move from:
6.29% to 6.54%.
Another could be paying even more.
The size of the change is identical.
The starting point is not.
That is why your starting mortgage rate can matter just as much as the RBA increase itself.
Existing Customers Should Check Their Actual Rate
Many people know the RBA cash rate.
Far fewer can immediately say what mortgage rate they personally pay.
That number should be the starting point.
Check your:
banking app,
latest home-loan statement,
internet banking,
or lender correspondence.
Then compare it with the rates available for borrowers with similar:
LVR,
loan size,
property purpose,
repayment type,
and loan features.
You cannot properly evaluate whether your loan remains competitive until you know your own starting rate.
Ask Your Bank for a Pricing Review
You do not necessarily need to refinance immediately.
The first conversation can be with your existing lender.
Ask whether it can review your current pricing.
Banks know competitors are competing for refinance customers.
A lender may offer:
a retention discount,
different product pricing,
or another structure.
There is no guarantee.
But asking can be considerably easier than switching banks.
If the lender will not improve the rate, you can then compare alternatives.
Do Not Compare Interest Rate Alone
The lowest headline mortgage rate is not automatically the cheapest loan.
A comparison should also consider:
annual package fees,
offset-account fees,
redraw,
application fees,
valuation costs,
discharge fees,
cashback incentives,
repayment flexibility,
and remaining loan term.
A borrower might save on the interest rate but lose money elsewhere.
Or a loan with a slightly higher rate could provide an offset feature that creates more value for someone who maintains a substantial cash balance.
Compare the whole structure.
Property Values Matter if You Want to Refinance
Mortgage rates are rising at the same time some Australian property markets are weakening.
That creates another complication.
Suppose your property was previously worth $800,000 and you owed $600,000.
Your LVR was:
75%.
If the property falls to $720,000 while your balance remains close to $600,000, your LVR rises to around:
83%.
That could affect:
available refinance pricing,
lender eligibility,
and potentially lenders mortgage insurance.
So finding a better advertised rate does not automatically mean you can access it.
Equity matters.
This Is Why Reviewing Early Can Be Better
Borrowers sometimes wait until repayments become uncomfortable before reviewing their loan.
But by then, options may have narrowed.
A property value may have fallen.
Household income may have changed.
Credit-card debt may have increased.
A fixed period may be close to expiring.
Or serviceability requirements may have tightened.
Reviewing the mortgage while the household is still financially comfortable can provide more flexibility.
The 9 October Date Gives Borrowers a Clear Trigger
For Big Four customers, 9 October is now a practical checkpoint.
Before or around that date, consider checking:
your existing mortgage rate,
your new rate after the increase,
your expected repayment,
your offset balance,
your available equity,
your remaining term,
and comparable market options.
The objective is not to panic and switch banks.
It is to understand your position.
Another Rate Increase Is Still Possible
The RBA's September statement did not say the tightening cycle was definitely finished.
The Board said it would continue doing what it considers necessary to return inflation sustainably to target, including increasing the cash rate further if needed. Reserve Bank of Australia
The major banks' economists are not unanimous about what comes next.
NAB currently forecasts the RBA to hold at 4.60%, although it says further tightening remains a risk. NAB
Other economists have kept the possibility of another increase on the table.
Borrowers therefore should not structure their finances around an assumption that 4.60% must be the peak.
Stress-Test One More Increase
A useful exercise is to calculate what another 0.25 percentage-point increase would do.
You do not need to believe it will happen.
You are simply testing resilience.
Ask:
Could we manage another $90 or $100 per month?
Could we absorb it without using credit cards?
Would we need to reduce savings?
Would we still be comfortable if rates remained elevated throughout 2027?
That gives a household more useful information than trying to perfectly predict the next RBA meeting.
The Bigger Lesson: The RBA Decision Has Now Become a Real Mortgage Change
On 29 September, the RBA increased the cash rate to 4.60%.
On 30 September, Australia's major lenders started confirming how that decision would flow through to customers.
Now the implementation dates are known.
For Big Four variable mortgage customers:
9 October.
For Macquarie variable home-loan reference rates:
15 October. ABC News
That removes much of the uncertainty around this particular increase.
Borrowers can now calculate.
Compare.
Budget.
And, where appropriate, negotiate.
The Big Four Have Made Their Move. Have You Checked Yours?
Another 0.25 percentage points can look small on paper.
But after repeated increases, the cumulative household impact can become substantial.
The major banks are passing this increase through in full.
That means now is a good time to understand exactly what you are paying and whether your home loan still suits your circumstances.
You cannot control the RBA.
You cannot control your bank's decision to pass on the increase.
But you can understand your mortgage and compare the options available to you.
Review Your Home Loan Before the New Rates Take Effect
Loan & Own Mortgages helps homeowners review their existing lending position and compare suitable options across its lender panel.
A mortgage review can consider:
your current rate,
new repayment amount,
equity and LVR,
offset structure,
loan features,
refinancing costs,
and alternative lender pricing.
The goal is not automatically to refinance.
It is to understand whether your existing loan remains competitive after another full rate increase.
Data sources
Reserve Bank of Australia, 29 September 2026: The RBA increased the cash-rate target by 25 basis points to 4.60%, citing elevated inflation and upside inflation risks. Reserve Bank of Australia
ABC News, 30 September 2026: Commonwealth Bank, NAB, Westpac and ANZ confirmed they will increase variable home-loan rates by the full 0.25 percentage points from 9 October. Macquarie's increase takes effect on 15 October. ABC News
Commonwealth Bank: CBA confirmed a 0.25 percentage-point increase to variable home-loan rates effective 9 October 2026. CommBank
NAB: NAB confirmed variable home-loan interest rates will increase 0.25 percentage points from 9 October. NAB
ANZ: Variable Australian home-loan rates will increase 0.25 percentage points from 9 October. ANZ
Westpac: New and existing variable home-loan customers will receive a 0.25 percentage-point increase effective 9 October. Westpac
Macquarie: Variable home-loan reference rates will increase by 0.25 percentage points effective 15 October. Macquarie Bank
This article provides general information only and does not constitute personal financial, credit, investment, tax or legal advice. Actual rate and repayment changes depend on the individual lender, mortgage balance, loan term, product structure and borrower circumstances.
